Secured Personal Loan Interest Rates: A Complete Guide
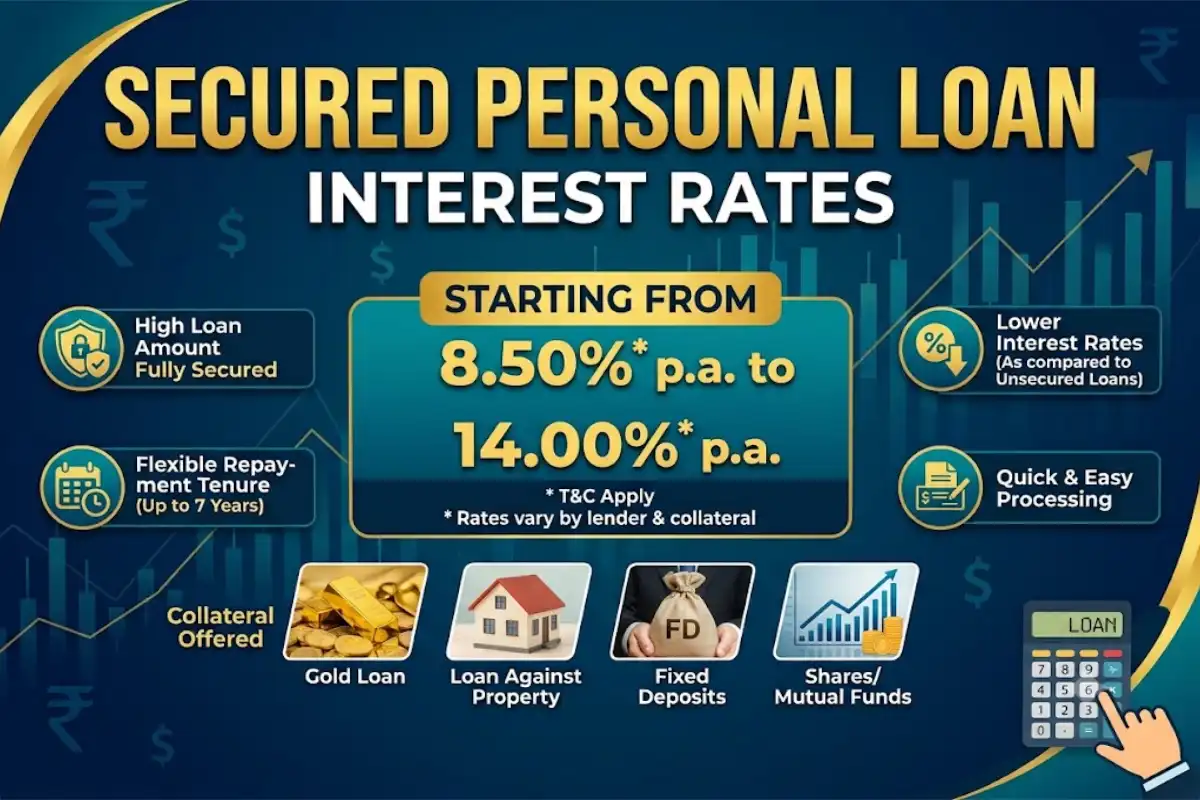
What Are Secured Personal Loans Secured personal loan options provide you with a loan secured against the value of an asset like a car, savings account, property, or other qualifying assets. Typically, secured personal loan interest rates are lower than those you might see on unsecured borrowing.
But you can’t pick your rate by just choosing the amount you want to borrow-your interest rate will also be based on your credit profile, amount you want to borrow, how long you want to pay it off, the value of the collateral, policies of the lender and your income.
This Article Belongs to Personal Loans
What Are Secured Personal Loan Interest Rates?
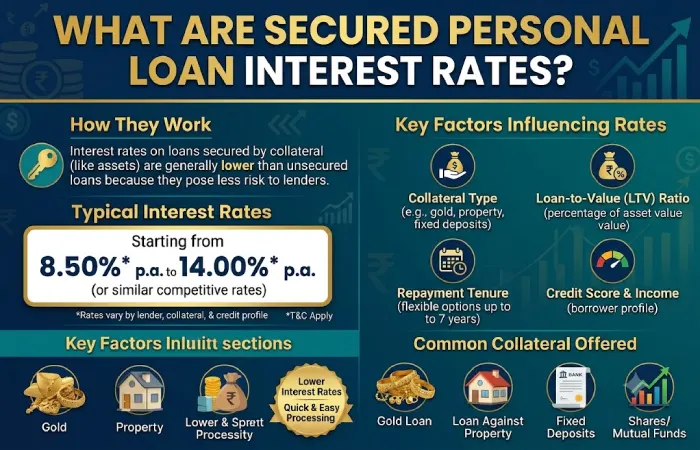
Secured personal loan interest rates Secured personal loan interest rates are the rates of interest payable on a personal loan where a security is provided. A bank or other lender may have a right of recourse to the security if the borrower fails to repay the loan according to the terms of the loan agreement and applicable law.
You may be able to get a lower rate on a secured loan, since the asset provides the lender with security, which means they will lose less if you don’t repay.
Factors That Affect Secured Loan Rates
| Factor | Potential impact on rate |
|---|---|
| Credit score and history | Stronger credit may help qualify for better rates |
| Income and employment | Stable income can support stronger loan eligibility |
| Collateral value | Higher-quality collateral may reduce lender risk |
| Loan amount | Rates can vary depending on the amount borrowed |
| Repayment term | Longer terms may have different pricing |
| Lender policies | Each lender uses its own underwriting criteria |
| Debt-to-income ratio | Lower existing debt may improve eligibility |
Secured Loan Interest Rates vs. Unsecured Rates
One of the main differences between secured and unsecured borrowing is collateral. An unsecured personal loan does not require an asset to secure the debt, while a secured loan does.
Because secured borrowing provides additional security to the lender, personal loan secured rates can be lower in some circumstances. However, a lower interest rate does not automatically make a loan cheaper. Borrowers should also consider fees, loan duration, collateral requirements, and other costs.
| Feature | Secured Personal Loan | Unsecured Personal Loan |
|---|---|---|
| Collateral | Usually required | Not usually required |
| Interest rate | May be lower | May be higher |
| Lender risk | Generally lower | Generally higher |
| Asset at risk | Yes, if pledged | No collateral asset |
| Approval factors | Credit, income and collateral | Primarily credit, income and debt profile |
Understanding Secured Loan APR
Consider the secured loan APR: To make a more valid comparison of loans, the initial interest rate alone may not be enough. The APR of a loan may give you a more comprehensive look at your borrowing costs, since there can be some included fees and charges.
For example, two lenders could quote comparable interest rates but charge different origination fees or fees that apply to other services. Comparing APR as well as the interest rate can give you a better overall view of the true cost.
Before accepting an offer, check the lender’s disclosures to understand exactly what is included in its APR.
How to Find a Low Interest Secured Personal Loan
Finding a low interest secured personal loan starts with comparing multiple offers rather than focusing on a single advertised rate.
Consider these steps:
- Optimize your credit profile: Update your credit history and rectify any errors or incomplete information.
- Shop around: compare interest rates, APRs, fees, repayment terms and whether collateral is needed.
- Select a suitable loan amount: Borrow as little as possible and as much as you can comfortably repay.
- Think about the loan term: Will a longer term lower your payment in return for paying more in interest?
- Inquire about any fees: including origination, valuation, processing, late-payment, prepayment or other fees.
- Know the collateral: Don’t assume it’s the asset you’re putting up for collateral; know precisely what’s going on in case there’s a problem.
Secured Personal Loan Costs to Consider
Interest is only one part of secured personal loan costs. Depending on the lender and loan structure, borrowers may encounter additional charges.
| Cost | What to check |
|---|---|
| Interest | Annual rate charged on the outstanding balance |
| APR | Broader annualised borrowing-cost measure |
| Origination or processing fee | Upfront or financed lender charge |
| Valuation fee | Possible cost of assessing collateral |
| Late-payment fee | Charge that may apply after missed payments |
| Prepayment fee | Possible charge for repaying early |
| Other charges | Review the loan agreement for additional costs |
Is a Secured Personal Loan Right for You?
A secured personal loan may be worth considering when you need financing and have an eligible asset that you are comfortable pledging as collateral. The potentially lower rate can make secured borrowing attractive in certain circumstances.
The main danger is that the asset used for security might be repossessed, foreclosed on, or otherwise seized if you miss payments. What could happen varies by collateral type, the lender agreement, and the law.
Before taking out the loan, look at the total amount you will repay, including the APR and costs, and the risks of the loan instead of selecting a loan based solely on the headline interest rate.
Final Thoughts
Personal loan interest rate quotes for secured loans depend on the lender and borrower. Providing collateral may lead to more competitive pricing for some, but it ultimately comes down to the interest rate, APR, fees, loan term and other terms.
Compare the APR on all secured personal loans First and foremost, it’s important to look beyond the headline rate of your secured personal loan, and also read the detailed terms of the loan agreement.