Credit Line on UPI vs Credit Card: Key Differences and Comparison
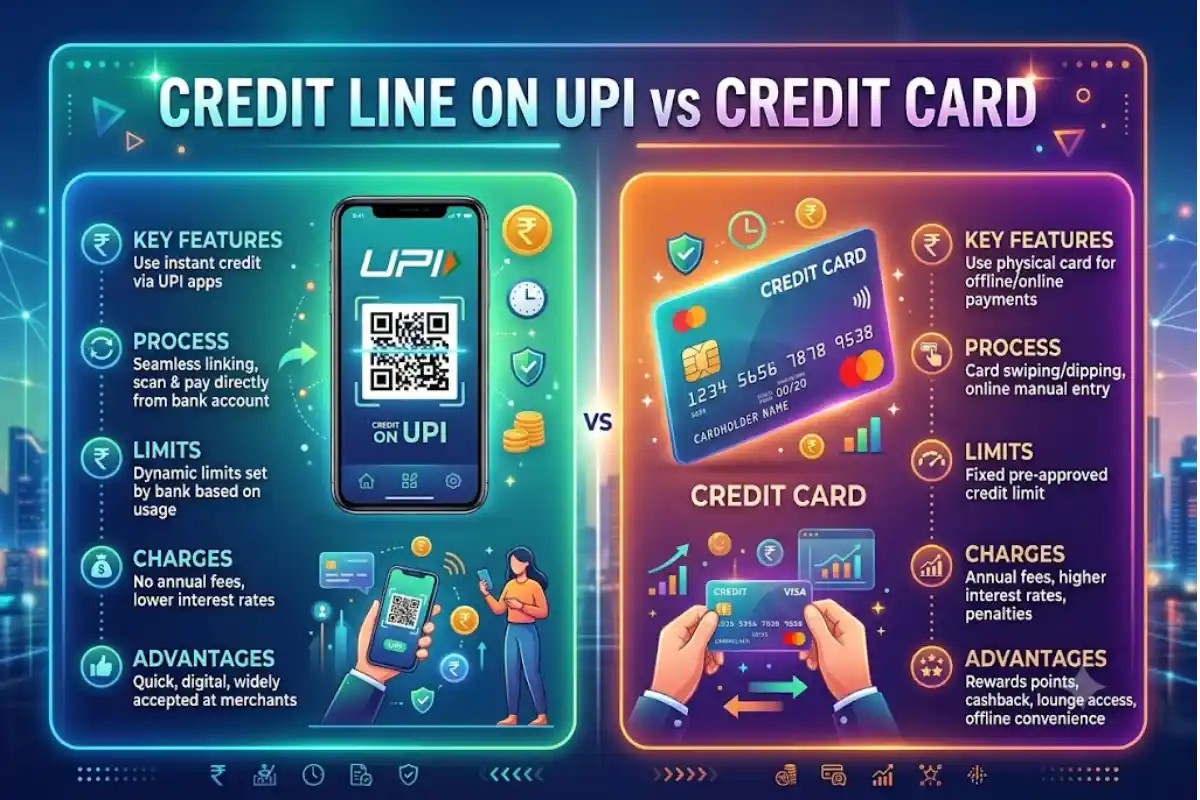
Digital payments have made it easier to access and use credit for everyday expenses. Two options that are increasingly relevant for consumers are a credit line on UPI and a traditional credit card. Although both allow users to make purchases using borrowed funds, their features, repayment structures, acceptance and costs can differ.
Understanding the UPI credit line vs credit card can help you choose the option that better matches your spending and repayment needs.
This Article Belongs to Credit Debt
What Is a Credit Line on UPI?
A credit line on UPI is a pre-sanctioned credit facility provided by a bank that can be used through UPI. The Reserve Bank of India (RBI) enabled the operation of pre-sanctioned bank credit lines through UPI in 2023.
Instead of using money directly from a savings account, an eligible customer can select the linked credit line when making a supported UPI payment. Interest and other charges depend on the bank and the terms of the specific credit facility.
Credit line availability, limits and eligible transactions can vary between banks.
The Reserve Bank of India (RBI) expanded UPI in September 2023 to allow pre-sanctioned credit lines at banks to be used as a funding account through UPI.
What Is a Credit Card?
Credit cards are a form of revolving credit offered by a bank or other financial institution to a borrower. The bank or financial institution that issues the credit card sets a credit limit when the card is issued and the holder can make card purchases up to the available credit limit.
Credit cards can offer features such as reward points, cashback, discounts, interest-free periods on eligible purchases and other benefits. However, interest can become expensive if the outstanding balance is not repaid according to the card’s terms.
RBI regulations govern credit card issuers and require issuers to follow applicable rules relating to issuance and conduct of credit cards.
UPI Credit vs Credit Card: Key Differences
The main difference between the two is how the credit facility is accessed.
| Feature | Credit Line on UPI | Credit Card |
|---|---|---|
| Payment method | UPI app/QR-based payment | Card, online payment or supported digital wallet/UPI |
| Credit facility | Pre-sanctioned bank credit line | Revolving credit facility |
| Physical card | Generally not required | Usually issued as a physical or virtual card |
| UPI payments | Designed for UPI transactions | UPI use depends on card/network eligibility |
| Credit limit | Determined by the lending bank | Determined by the card issuer |
| Interest | Depends on credit-line terms | Depends on card terms and repayment |
| Rewards | Depends on the product | Many cards offer rewards or cashback |
| Repayment | According to the credit-line agreement | Usually through monthly card bills |
| Acceptance | Mainly where supported through UPI | Broad card acceptance plus eligible digital channels |
Credit Line vs Credit Card: How Do They Work?
With a credit line on UPI, the customer can make an eligible UPI payment using available credit instead of directly debiting a bank account. The credit line acts as the funding source for the transaction.
With a credit card, the issuer pays the merchant for an eligible transaction and the cardholder subsequently repays the issuer. The cardholder may have a billing cycle and a minimum amount due, although paying the full outstanding balance can help avoid applicable interest charges.
Therefore, the credit line vs credit card comparison is not simply about which one provides credit. It is also about how the credit is accessed, used and repaid.
UPI Credit Card vs Credit Line: Which Features Matter?
When comparing a UPI credit card vs credit line, consider these factors:
1. Payment Convenience
A UPI credit line can be convenient for people who regularly use UPI QR codes and UPI-enabled merchant payments. A credit card can provide more payment options, including card terminals, online checkout and eligible UPI transactions.
2. Interest and Fees
Neither option should be compared solely on the headline credit limit. Check the interest rate, processing fees, late-payment charges and other applicable costs before using borrowed money.
3. Rewards and Benefits
Traditional credit cards often provide structured reward programmes, cashback, travel benefits or merchant offers. A credit line may or may not provide similar benefits, depending on the financial institution and product.
4. Acceptance
UPI has extensive merchant acceptance in India, but the availability of a particular credit line depends on the bank and supported UPI functionality. Credit cards can be useful where card payments are accepted but UPI is unavailable.
Credit Line or Credit Card: What Should You Consider?
To decide on credit line or credit card, consider your spending pattern and the features you actually need.
A UPI credit line can be helpful if you mostly pay everyday bills through UPI and your bank offers a compatible product. A credit card can be more helpful if you’re looking for wider acceptance, rewards, billing-cycle features, or point-based card benefits.
Compare the interest rate, charges, credit limit, repayment cycle, rewards, acceptance by merchants, and criteria to qualify, before opting for either of these options.
UPI Credit Comparison: Key Takeaways
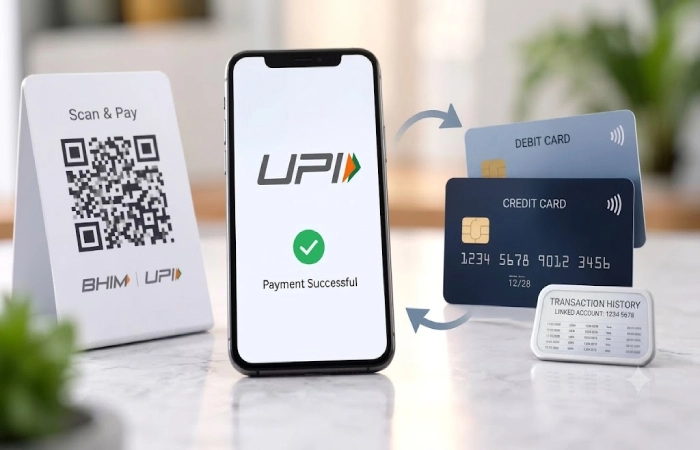
A proper UPI credit comparison shows that both products provide access to borrowed money but are designed around different payment experiences. A credit line on UPI integrates credit directly into the UPI payment process, while a credit card combines a revolving credit facility with card-based payment functionality.
Another aspect to keep in mind is that UPI and credit cards don’t always fight each other. RBI has allowed eligible RuPay credit cards to be added to UPI, thus enabling credit-card transactions over supported UPI channels.
Finally, compare the terms offered by your own bank or card issuer instead of assuming that one type of credit will always cost less or offer additional benefits. Borrow only what you can manage to repay comfortably and be sure to verify all of the charges that are applicable before the facility is used.
Frequently Asked Questions
Is a credit line on UPI the same as a credit card?
No. A credit line on UPI is a pre-sanctioned credit facility that can be used through supported UPI payments, while a credit card is a revolving credit facility accessed through card-based payment channels and other eligible methods.
Can a credit card be used with UPI?
Eligible RuPay credit cards can be linked to UPI under the applicable framework. Availability and supported transactions depend on the issuer and UPI service.
Which has lower interest, UPI credit or a credit card?
There is no universal rate. Interest and fees depend on the specific credit-line or credit-card product, so compare the applicable terms before borrowing.
Can a UPI credit line replace a credit card?
Not necessarily. A UPI credit line may cover many everyday UPI payments, but a credit card can offer additional payment channels, rewards and other features.
This version is kept within the 900-word limit and uses the requested secondary keywords naturally without keyword stuffing.