How Credit Line on UPI Works: A Complete Guide
Last Updated: September 15, 2026
Digital payments in India have evolved beyond traditional bank-account-based transactions. One such development is the ability to use a credit line through UPI for eligible purchases. This facility allows customers to make UPI payments using a pre-approved credit limit instead of directly debiting their savings account.
Understanding how credit line on UPI works can help users make informed decisions about eligibility, payments, charges, and repayment.
The Reserve Bank of India (RBI) expanded the scope of UPI to enable payments financed through pre-sanctioned credit lines at banks, allowing eligible customers to use credit as a funding source for UPI transactions.
This Article Belongs to Credit Debt
What Is a Credit Line on UPI?
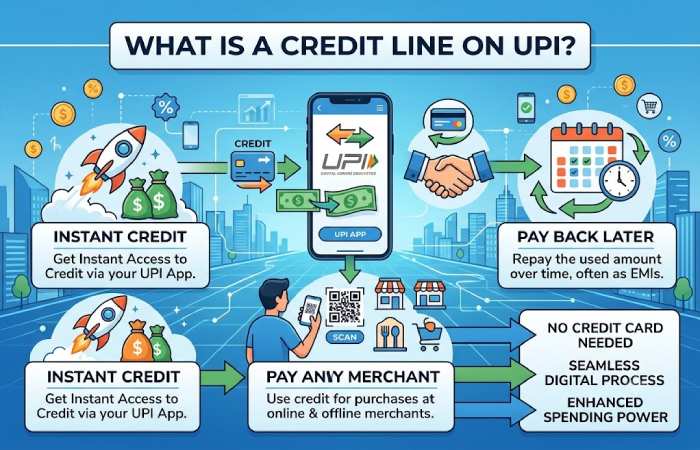
A credit line on UPI is a pre-approved credit facility linked to a UPI-enabled account or app. Instead of using money already available in your bank account, eligible users can pay merchants using the sanctioned credit limit.
The Reserve Bank of India (RBI) has enabled scheduled commercial banks to offer pre-sanctioned credit through UPI and has provided a framework for doing so, subject to extant terms and conditions.
Put simply, it is not quite a credit card but for all eligible UPI transactions, its features, rate of interest, charges, usage limit etc. will be determined by the bank and product.
How Credit Line on UPI Works
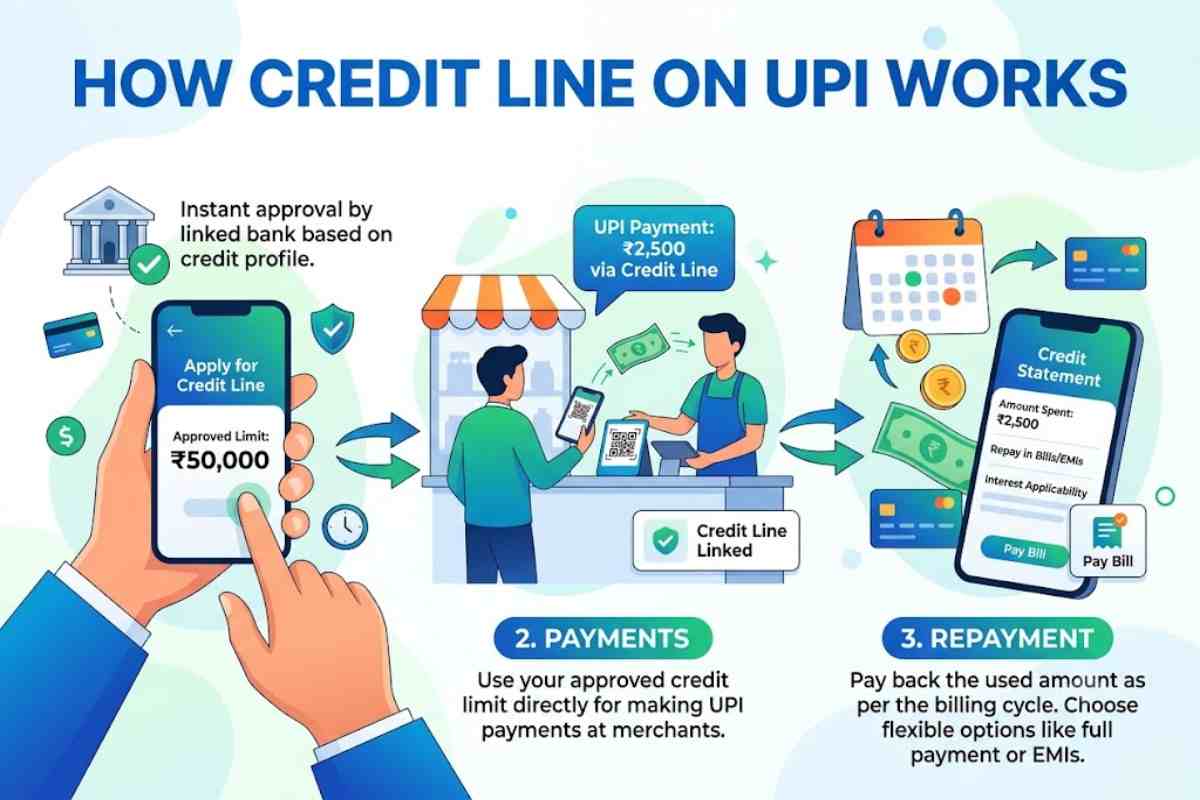
The basic process is straightforward:
- A bank assesses the customer’s eligibility and approves a credit limit.
- The credit line is made available through a supported UPI app.
- The customer links or activates the credit facility.
- At an eligible merchant, the customer selects the credit line as the payment account.
- The transaction amount is deducted from the available credit limit.
- The customer repays the amount according to the bank’s repayment terms.
For example, suppose your bank provides a ₹50,000 credit line and you use ₹2,000 for a UPI purchase. Your available limit may then reduce to ₹48,000, subject to the product’s terms.
Credit Line on UPI vs Bank Account UPI
| Feature | Regular UPI | Credit Line on UPI |
|---|---|---|
| Payment source | Bank account | Approved credit facility |
| Uses existing balance | Yes | No |
| Credit limit | Not applicable | Pre-approved limit |
| Repayment | Not required | Required |
| Interest/charges | Usually no borrowing cost | Depends on the credit product |
| Eligibility | UPI-enabled bank account | Bank-approved customers |
What Is a UPI Credit Line Payment?
A UPI credit line payment is a merchant payment made using the available balance of a sanctioned credit facility rather than the user’s bank-account balance.
The customer generally scans a QR code or selects UPI at checkout. If the merchant and transaction are eligible, the user can choose the linked credit line as the payment source.
This can provide additional flexibility when making everyday purchases, but users should understand the repayment obligations before using borrowed funds.
How UPI Credit Line Works for Customers
The exact process can differ between banks and UPI apps, but the general flow is:
Credit approval → Credit line activation → UPI payment → Credit utilisation → Repayment
The bank determines the customer’s credit limit based on its internal eligibility and underwriting criteria. Once activated, the credit line can potentially be used at eligible merchants accepting UPI payments.
The available limit changes as customers use and repay the credit.
Pre-Approved Credit Line UPI: Who Can Use It?
A pre-approved credit line UPI facility is not automatically available to every UPI user. The issuing bank decides eligibility based on its credit policies.
Factors may include:
- Existing relationship with the bank
- Credit history
- Income and repayment capacity
- Internal risk assessment
- Product-specific eligibility criteria
Banks may also impose transaction, merchant-category, or usage restrictions.
Where Can Credit Through UPI Be Used?
Credit through UPI is primarily designed for eligible merchant transactions. Depending on the product, it may be usable at physical stores, online merchants, or other supported payment points.
However, not every UPI transaction can necessarily be funded by a credit line. Person-to-person transfers and certain categories may be restricted.
Users should check the terms provided by their bank before assuming that the credit facility works for all UPI payments.
UPI Credit Facility: Benefits and Limitations
| Benefits | Limitations |
|---|---|
| Convenient digital payments | Borrowed money must be repaid |
| No need to maintain sufficient bank balance for each purchase | Interest or fees may apply |
| Can provide short-term payment flexibility | Credit limit is subject to approval |
| Integrated with supported UPI payments | Some transactions may be restricted |
| Can be useful for eligible merchant purchases | Late repayment can increase costs |
How to Repay UPI Credit Payments
A UPI credit payment creates a repayment obligation. The repayment process depends on the issuing bank and the specific credit product.
Before using the facility, check:
- Billing or repayment cycle
- Interest rate
- Minimum amount due, if applicable
- Late-payment charges
- Applicable fees
- Available repayment methods
Paying on time is important because missed payments can increase borrowing costs and may negatively affect your credit profile, depending on the product and reporting practices.
Is Credit Line on UPI Safe?
Credit Line on UPI uses the UPI payment infrastructure and banking systems, but users should still follow standard digital-payment precautions. Never share your UPI PIN, OTP, card details, or banking credentials with another person.
Also remember that a UPI PIN authorises a payment; it should not be entered simply to receive money.
For official information about UPI and payment-system regulations, users can refer to the Reserve Bank of India (RBI) and National Payments Corporation of India (NPCI).
Final Thoughts
Understanding how credit line on UPI works is important before using this borrowing facility. It allows eligible customers to make supported merchant payments using a pre-approved credit limit rather than directly using their bank balance.
While it may be an added convenience, the system should never be considered a free-ride. When comparing the rates, fees, repayment limits, and differences in transactions that are allowed between the primary account and the UPIC account, users can determine if it is right for them.
FAQs
1. What is a credit line on UPI?
It is a pre-approved credit facility that eligible customers can use for supported UPI merchant payments.
2. How UPI credit line works?
The bank provides a credit limit, and eligible users can select that credit facility as the payment source for supported UPI transactions.
3. Can I use a UPI credit line for every payment?
No. Usage depends on the bank, UPI app, merchant, transaction type, and applicable restrictions.
4. Is UPI credit the same as a bank balance?
No. A bank balance represents available funds, while a credit line represents borrowed funds that must be repaid according to its terms.
5. Does a UPI credit line charge interest?
Charges depend on the specific credit product and its terms. Users should check the issuing bank’s applicable interest rates and fees.