Types of Collateral for Secured Personal Loans
A secured personal loan is a form of borrowing in which the lender requires collateral against the debt. This reduces risk for the lender, since the collateral can be seized or sold in the event that the borrower does not keep up with repayments on the loan.
Knowing the kinds of collateral for secured personal loans can help you select an asset that is best suited for your financial resources. Secured personal loan lenders can require you to use your savings, investment, property, car, or other valuable possessions as collateral.
This Article Belongs to Personal Loans
What Is Collateral for a Secured Personal Loan?
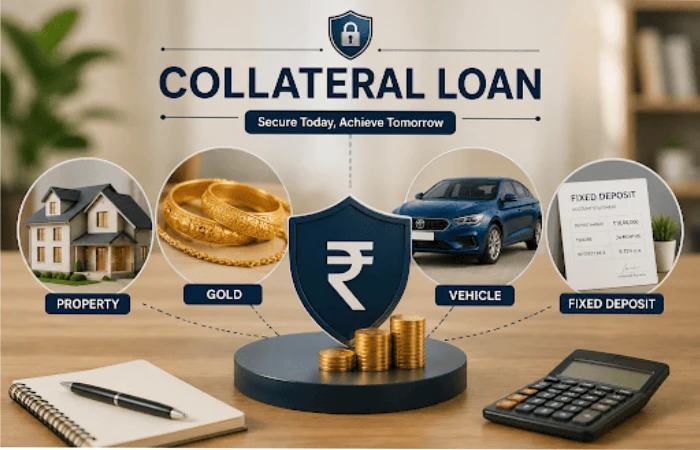
Collateral is an asset that a borrower offers to a lender when applying for a secured loan. The lender receives a legal interest in the asset until the loan is paid back in full, per the terms of the agreement.
Borrowers can also refer to the Reserve Bank of India (RBI) financial education resources to better understand loan-related concepts, including secured and unsecured borrowing.
A secured personal loan might have benefits including the possibility of a cheaper rate of interest or higher borrowing limit compared to some unsecured loans. Exact conditions will vary by lender, credit score and history of borrower, amount and type of loan offer.
Common Types of Collateral for Loans
Different lenders accept different assets. Some of the most common assets used as collateral include:
| Type of Collateral | How It May Be Used | Key Consideration |
| Savings account or fixed deposit | Savings or deposit is pledged against the loan | Funds may be restricted until repayment |
| Vehicle | Car, two-wheeler, or other eligible vehicle may secure the loan | Vehicle value and ownership matter |
| Real estate | Property may be pledged as security | Documentation and valuation are generally required |
| Investments | Eligible securities or investments may be pledged | Eligibility varies by lender |
| Gold | Eligible gold assets may be accepted by certain lenders | Purity and valuation affect loan amount |
| Other valuable assets | Certain lenders may accept specific assets | Acceptance depends on lender policy |
1. Savings or Fixed Deposit
A savings secured loan uses money held in an eligible savings account, fixed deposit, or similar deposit as security. Instead of selling the deposit, the lender may place a hold or lien on it while the loan remains outstanding.
This option can be useful for borrowers who want to access credit while retaining their underlying deposit, although the account or deposit may have restrictions during the loan period.
2. Vehicle
A vehicle can sometimes serve as collateral for a collateral-backed loan. Depending on the lender and loan structure, the vehicle’s age, condition, market value, and ownership documents may affect eligibility.
Borrowers should check whether they can continue using the vehicle normally and what happens if repayments are missed.
3. Real Estate
Residential or other eligible property can potentially be used as security for borrowing. Since property generally has a higher value than many other assets, it may support larger loans.
However, property-backed borrowing usually involves documentation, ownership verification, valuation, and other lender requirements. Borrowers should also understand the consequences of default because the property is being offered as security.
4. Investments and Securities
Certain financial investments may qualify as secured loan collateral. Depending on the lender, eligible assets could include specific securities, bonds, or other investment products.
The lender may place a lien or otherwise restrict the pledged investments until the loan is repaid. Market-linked assets can also change in value, so borrowers should understand the lender’s requirements regarding collateral value.
5. Gold and Other Valuable Assets
Some lenders offer loans secured against eligible gold or other valuable assets. The loan amount generally depends on the assessed value and eligibility of the collateral.
Borrowers should carefully review valuation methods, interest rates, fees, repayment terms, and the lender’s policy concerning the asset before proceeding.
How Collateral Affects a Secured Personal Loan
The collateral does not automatically guarantee approval. Lenders may also consider income, credit history, existing debt, repayment capacity, employment or business profile, and other eligibility criteria.
The relationship between the asset and loan can generally be understood as follows:
Asset pledged → Lender assesses value → Loan terms determined → Collateral remains secured → Loan repaid → Security released
If the borrower defaults, the lender may have rights over the collateral according to the loan agreement and applicable laws.
Benefits and Risks of Using Collateral
| Benefits | Risks |
| May provide access to secured borrowing | The pledged asset is at risk if the borrower defaults |
| Potentially competitive interest rates | Some assets may be restricted during the loan |
| May support a higher loan amount | Valuation and documentation may be required |
| Can provide an alternative to unsecured borrowing | Additional fees or conditions may apply |
How to Choose the Right Collateral
Before choosing collateral, consider:
- Asset value: Make sure the asset is sufficient for the required loan.
- Ownership: Confirm that you have the legal right to pledge it.
- Liquidity: Consider how important the asset is to your financial security.
- Loan cost: Compare interest rates, processing fees, and other charges.
- Default consequences: Understand exactly what can happen to the asset if you cannot repay.
- Lender requirements: Different lenders have different collateral eligibility rules.
Conclusion
The types of collateral for secured personal loans can range from savings and fixed deposits to vehicles, property, investments, gold, and other eligible assets. A secured loan can provide borrowers with another way to access financing, but pledging an asset also creates additional risk.
Compare the lender’s interest rate, charges, eligibility, collateral valuation procedure, instalment terms, and the default conditions before enrolling for a collateralised personal loan. Consider their value as well as the relative significance of the asset you employ as collateral when making a decision to take collateral.