Inflation & Retirement Planning: Calculate Your Future Retirement Needs
Retirement planning involves more than accumulating a huge corpus; your hard earned savings should also last you as long as you need them. Inflation will push up prices over time, and the amount you’ll need to sustain your lifestyle post retirement will be very different from what you need now.
Save, Save, Save When you know how to plan for inflation in retirement, you can start to estimate what expenses will be in the future, determine how much money you need to save, and safeguard the buying power of your money in retirement.
This Article Belongs to Retirement Planning
What Is Inflation & Retirement Planning?
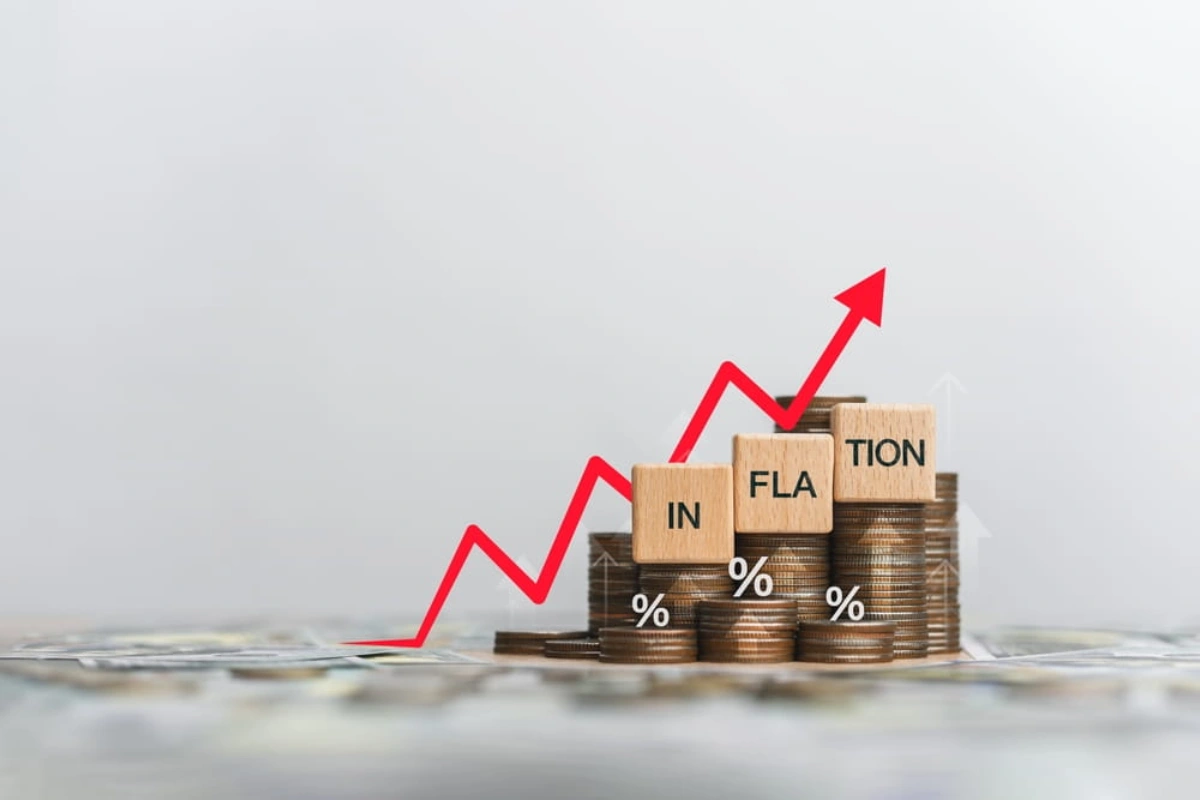
What exactly is inflation? Inflation is a general rise in prices over a period of time. In the context of your retirement, today’s 50,000 of monthly household expenses could be 30,000 or 60,000 in 15, 20, or 30 years, respectively.
For instance, at a current expense of 50,000 a month and 6% inflation, you can be certain that in 10 or 15 years’ time you will require significantly more income to sustain the same Standard of Living.
Therefore, retirement planning should consider:
- Current monthly and annual expenses
- Expected retirement age
- Years remaining until retirement
- Expected inflation rate
- Investment returns
- Retirement duration
- Healthcare and other rising expenses
How Inflation Affects Retirement Expenses
Inflation affects you more and more as the years pass, because it is compounded.
The cost of an expense in the future can be calculated as:
Future Cost = Cost Today x (1 + inflation rate)n, where n is the number of years in future in which the cost will occur.
For example, if you are currently spending Rs 6 lakh a year on retirement expenses. Assume inflation of 6% for 20 years.
| Particular | Value |
|---|---|
| Current annual expense | ₹6 lakh |
| Expected inflation | 6% |
| Period | 20 years |
| Approx. future annual expense | ₹19.24 lakh |
Hence why a measure only of today’s expenses can leave your retirement nestegg short of the mark.
What Is a Retirement Inflation Calculator?
A retirement inflation calculator can give you an idea of how much your expenses will grow by the time you retire. It can be handy if you’re trying to work out how much you’ll need to be saving and investing each month.
For example, you can enter:
- Current monthly expenses
- Expected inflation rate
- Years until retirement
- Expected investment return
- Current retirement savings
- Desired retirement age
The calculator can then help estimate your future expenses and the potential corpus required. However, calculator results depend heavily on the assumptions used. Actual inflation, investment returns, taxes, healthcare expenses and lifestyle costs may differ.
Calculating the Future Cost of Retirement
The calculation of future retirement costs is an important factor in pension planning.
Let’s say your current monthly expenses are 60,000 and you plan to retire 20 years down the line. At a hypothetical inflation rate of 6 per cent, your expenses at the time of retirement may be around 1.93 lakh per month.
| Current Monthly Expense | Inflation | Years | Approx. Future Monthly Expense |
|---|---|---|---|
| ₹40,000 | 6% | 20 | ₹1.28 lakh |
| ₹50,000 | 6% | 20 | ₹1.60 lakh |
| ₹60,000 | 6% | 20 | ₹1.92 lakh |
| ₹75,000 | 6% | 20 | ₹2.41 lakh |
| ₹1,00,000 | 6% | 20 | ₹3.21 lakh |
These figures are illustrations and should be adjusted according to your own assumptions.
What Is an Inflation-Adjusted Retirement Corpus?
An inflation adjustment retirement corpus is a savings for retirement that is being computed, taking future inflation into account.
A fixed number like 1 crore or 2 crore may not be enough though. This is because the value of the money will be dictated by when you plan to retire and for how long the corpus will support you.
For instance, something that is valued at 1 crore now will not have the same value after 20 years, if inflation persists.
Your retirement corpus should therefore account for:
- Inflation before retirement
- Inflation during retirement
- Expected investment returns
- Life expectancy
- Healthcare costs
- Taxes and other expenses
- Emergency reserves
Protecting Retirement Purchasing Power
Retirement buying power is how much material things can be bought with your income.
You could also help that protection by devising a bucket list investment strategy rather than placing all your eggs in the asset class that cannot keep up with inflation.
Some approaches include:
| Strategy | Potential Role |
|---|---|
| Equity investments | Long-term growth potential |
| Debt investments | Stability and income |
| Fixed-income products | Predictable returns |
| Real estate | Potential long-term asset growth |
| Emergency fund | Covers unexpected expenses |
The appropriate allocation depends on your risk tolerance, time horizon and financial circumstances.
How to Include Inflation in Retirement Planning
It’s wise to do this now and then.
1: Calculate your current annual expenses.
2: Come up with a reasonable long-term inflation assumption.
3: Project your expenses until retirement.
4: Make a Time Horizon Estimate for Your Retirement Corpus.
5: Consider expected investment returns.
6: Calculate the required retirement corpus.
7: Re-evaluate your investments and step up your contributions when your salary rises.
Conclusion
The rate of inflation can have a tremendous impact on the number of many to financially sustain your livelihood after you retire. Including inflation in your estimates allows you to determine how much you will need in retirement, build your inflation adjusted retirement corpus, and preserve your retirement buying power.
Reconsider your fixed retirement goal Review your costs, your savings contributions and your assumptions at regular intervals. A plan that accommodates changing costs could be the more realistic base for your planning.