Money Management International Debt Management Plan: How MMI DMP Works
How a Money Management International Debt Management Plan Works Managing numerous credit card accounts becomes problematic when the majority of each payment goes towards interest and minimum payment. A Money Management International Debt Management Plan (MMI DMP) can assist qualified consumers to consolidate manageable amounts of unsecured debt with one easy monthly payment.
Money Management International (MMI) is a nonprofit credit counselling organisation that provides debt management services. Its DMP is not a loan or debt-consolidation loan. Instead, MMI works with creditors and distributes a consumer’s monthly payment among participating creditors.
This Article Belongs to Money Management
What Is an MMI Debt Management Plan?
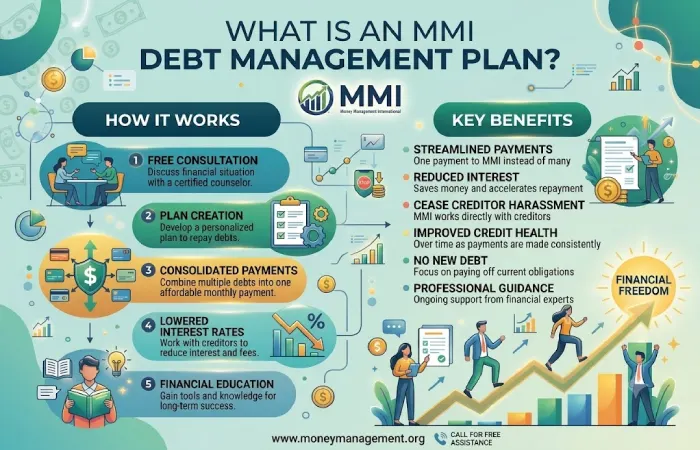
An MMI debt management plan is a structured repayment programme for people struggling with eligible unsecured debt, such as credit card balances. Rather than paying several creditors separately, you generally make one monthly payment through MMI.
MMI reviews your income, expenses and debts before determining whether a DMP is appropriate. If you enrol, the organisation works with participating creditors to establish repayment arrangements that may include reduced interest rates.
Unlike a consolidation loan, an MMI DMP does not replace your existing debts with a new loan. Your original creditors remain the creditors, while MMI helps administer the repayment process.
How Does Money Management International DMP Work?
The Money Management International DMP process generally involves several stages:
- Financial assessment: MMI reviews your debts, income and expenses.
- Plan development: A counsellor determines whether a debt management plan could fit your financial situation.
- Creditor arrangements: MMI works with participating creditors regarding repayment terms and interest rates.
- Single monthly payment: You make a payment to MMI, which distributes the appropriate amounts to creditors.
- Ongoing repayment: You continue making scheduled payments until the included debts are paid.
MMI says clients can complete a financial analysis before deciding whether to begin a DMP.
What Debts Can an MMI DMP Help With?
A DMP is primarily intended for unsecured debt. These are debts that are not backed by property or another asset. Credit card debt is a common example.
| Debt type | Generally associated with DMPs |
|---|---|
| Credit card debt | Yes |
| Other qualifying unsecured debt | May be eligible |
| Mortgage | Generally not |
| Car loan | Generally not |
| Secured loans | Generally not |
Eligibility depends on the creditor, account and individual circumstances, so consumers should confirm which debts can be included before enrolling.
MMI Debt Management Fees
Using an MMI debt management service may involve both an initial setup fee and an ongoing monthly fee. MMI states that fees vary according to factors such as location and the amount of debt being repaid. Its current information gives an average setup fee of around $38 and an average monthly fee of $35, although actual fees can differ.
The organisation also states that fees are subject to applicable limits and that consumers receive details about charges as part of the DMP documentation.
Benefits of MMI Debt Repayment
An MMI debt repayment plan can provide several practical advantages for consumers who qualify.
One Monthly Payment
Instead of managing several payments independently, a DMP combines payments for included accounts into one monthly payment administered through MMI.
Potentially Lower Interest Rates
MMI works with creditors to seek reduced interest rates for qualifying accounts. This can help more of each payment go towards reducing the principal balance. MMI reported an average interest rate of 7.66% for accounts on its repayment plans in 2025.
Structured Repayment
A fixed repayment structure can make it easier to track progress and budget for monthly debt payments.
No New Loan
An MMI DMP does not require taking out a new consolidation loan. The existing debts remain with the original creditors.
Can an MMI DMP Affect Your Credit?
A debt management programme can affect how accounts appear on your credit report. MMI explains that a DMP itself is not a loan and is not listed as a creditor on your credit report. However, accounts included in a DMP may be reported as being paid through a debt management plan while the programme is active.
Consumers should therefore consider their complete financial situation and understand how participating accounts may be reported before enrolling.
How to Start an MMI DMP
The first step is generally a financial review. You may need information about your credit cards, balances, income, expenses and other financial obligations. MMI says that having recent bills, bank statements and monthly statements available can help with the assessment.
If a DMP is appropriate, MMI provides instructions for completing the agreement and setting up automated deposits. The plan officially begins after the required initial payment process is completed.
Frequently Asked Questions
Is MMI DMP a loan?
No. An MMI DMP is a repayment arrangement rather than a loan. Your existing creditors continue to hold the debts.
How long does MMI debt management take?
The timeframe depends on the amount of debt, monthly payment and creditor arrangements. MMI says many DMPs are designed to be completed within five years or less.
Does MMI guarantee lower interest rates?
No specific result should be assumed for every account. Interest-rate reductions depend on creditor arrangements and individual circumstances.
Can you cancel an MMI DMP?
MMI states that its DMP can be cancelled, although consumers should review their agreement and understand the consequences before doing so.
Final Thoughts
A Money Management International Debt Management Plan may allow you to make one monthly payment to pay off certain qualified unsecured debt. The MMI DMP can include reduced interest rates and budget counseling, but it’s essential to know the costs, creditors involved, accounts eligible and how it may affect your credit before getting started.
Consumers should go through their own personal finances carefully and verify the current terms directly from MMI, before selecting a method of debt repayment.