Crypto Tax in India: Rates, TDS, Rules and Crypto Gains
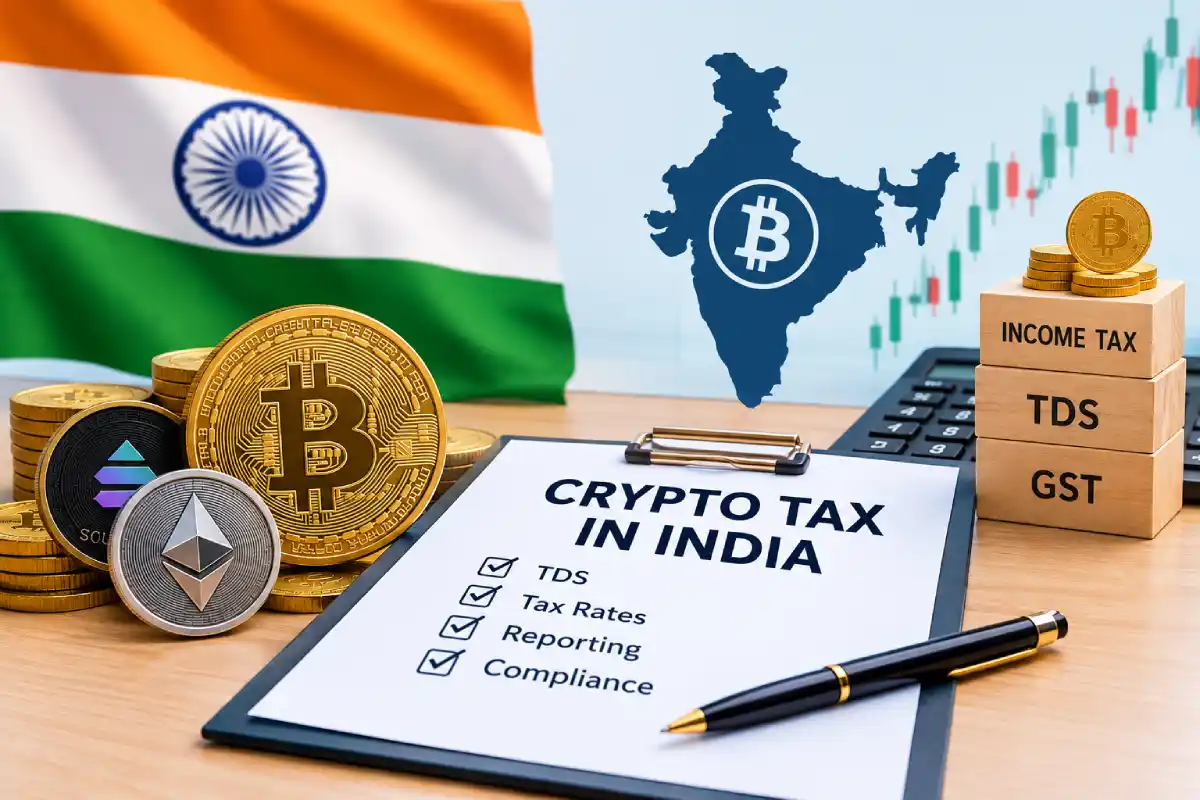
Taxation of cryptocurrency in India It is taxed under the tax regime for Virtual Digital Assets (VDA). The sale of digital assets like Bitcoin and other qualified crypto assets can generate tax liabilities when they are transferred. From the perspective of taxation, income from transfer of VDAs, as per the current law, is taxed at the rate of 30%, including applicable surcharge and 4% health and education cess.
Crypto Tax India Rules Everyone Should Know There are reasons why traders and also, investors should understand about crypto tax india rules, as taxes on cryptocurrency are not treated like many other investments.
This Article Belongs to Crypto Investing
What Is Crypto Tax in India?
India does not have a separate cryptocurrency income-tax rate called a “crypto tax.” Instead, qualifying cryptocurrency transactions fall within the Virtual Digital Asset (VDA) tax framework.
Under Section 115BBH, income arising from the transfer of a VDA is taxed at 30%. The calculation generally allows the cost of acquisition to be deducted, but other expenses or allowances are not deductible under this provision. Losses from VDA transfers also cannot be set off against other income or carried forward under Section 115BBH.
VDA Tax India: How Does It Work?
The tax applies to income from the transfer of qualifying VDAs. For example, if you purchase cryptocurrency and later sell it for a higher value, the resulting taxable income is generally calculated using the sale consideration minus the acquisition cost.
| Particular | Example |
|---|---|
| Purchase price | ₹2,00,000 |
| Sale value | ₹3,00,000 |
| Taxable VDA income | ₹1,00,000 |
| Tax at 30% | ₹30,000 |
| 4% cess on ₹30,000 | ₹1,200 |
| Tax before surcharge | ₹31,200 |
The actual tax liability can vary because surcharge and other applicable provisions may also apply.
Tax on Cryptocurrency India: Which Transactions Matter?
The tax framework focuses on the transfer of VDAs. Depending on the transaction, this can include selling crypto for Indian rupees or transferring one digital asset for another.
Crypto investors should maintain detailed records of:
- Purchase date and price
- Sale or transfer date
- Sale value
- Cost of acquisition
- Exchange and transaction records
- TDS deducted
- Wallet transaction history
Keeping these records can make it easier to calculate taxable income and also, complete the relevant tax return disclosures.
Crypto TDS India: What Is Section 194S?
In addition to the 30% tax on VDA income, India has a 1% TDS requirement under Section 194S for payments made to a resident as consideration for transferring a VDA, subject to the applicable threshold.
The threshold is generally:
| Payer category | Annual consideration threshold |
|---|---|
| Specified person | ₹50,000 |
| Other persons | ₹10,000 |
For a specified person, the rule include an individual or HUF with business turnover/professional receipts below the specified limits or an individual or HUF with no business/professional income.
When will you deduct TDS? As per section 194S, TDS is to be deducted at the time of the payment or credited to the account whichever is earlier. 1% TDS on crypto is not the crypto tax, it is a TDS which can be shown up in the calculation of your total tax liability.
How Are Crypto Gains Taxed?
Suppose an investor purchases Bitcoin for ₹5 lakh and later sells it for ₹7 lakh.
Crypto gain = ₹7 lakh − ₹5 lakh = ₹2 lakh
At a 30% rate, the basic tax on the ₹2 lakh taxable gain would be ₹60,000, before applicable cess and surcharge.
Importantly, Section 115BBH does not provide the usual deduction of expenses other than the cost of acquisition, and VDA losses cannot be set off against other income under this provision.
How to Report Crypto Income in Your ITR
The Income Tax Department provides a separate Schedule VDA in ITR-2 and ITR-3 for reporting VDA income on a transaction-wise basis. VDA income is subject to the special 30% rate.
Taxpayers should reconcile their exchange statements, transaction history and TDS information before filing their return.
New Crypto-Asset Reporting Requirements
India has also introduced reporting provisions concerning crypto-asset transactions. Section 285BAA requires prescribed reporting entities to furnish information about specified crypto-asset transactions in the prescribed manner.
This makes accurate record-keeping increasingly important for crypto investors.
Key Crypto Tax Rules at a Glance
| Rule | Current treatment |
|---|---|
| VDA tax rate | 30% |
| Applicable cess | 4% health and education cess |
| Deduction allowed | Cost of acquisition |
| Other expense deduction | Generally not allowed |
| VDA loss set-off | Not permitted under Section 115BBH |
| TDS on qualifying VDA transfer | 1% under Section 194S |
| ITR disclosure | Schedule VDA in ITR-2/ITR-3 |
Final Thoughts
India’s crypto tax India framework treats qualifying cryptocurrencies and other VDAs under specific tax provisions rather than the normal tax treatment applicable to many traditional investments. The key points are the 30% tax on VDA income, 1% TDS under Section 194S where applicable, restrictions on deductions and also, losses, and transaction-wise reporting requirements.
Because tax rules and filing provisions can change, investors should check the latest Income Tax Department guidance and consult a qualified tax professional for transactions involving significant amounts or complex situations.