Monthly Savings Needed for Retirement: How Much Should You Save?
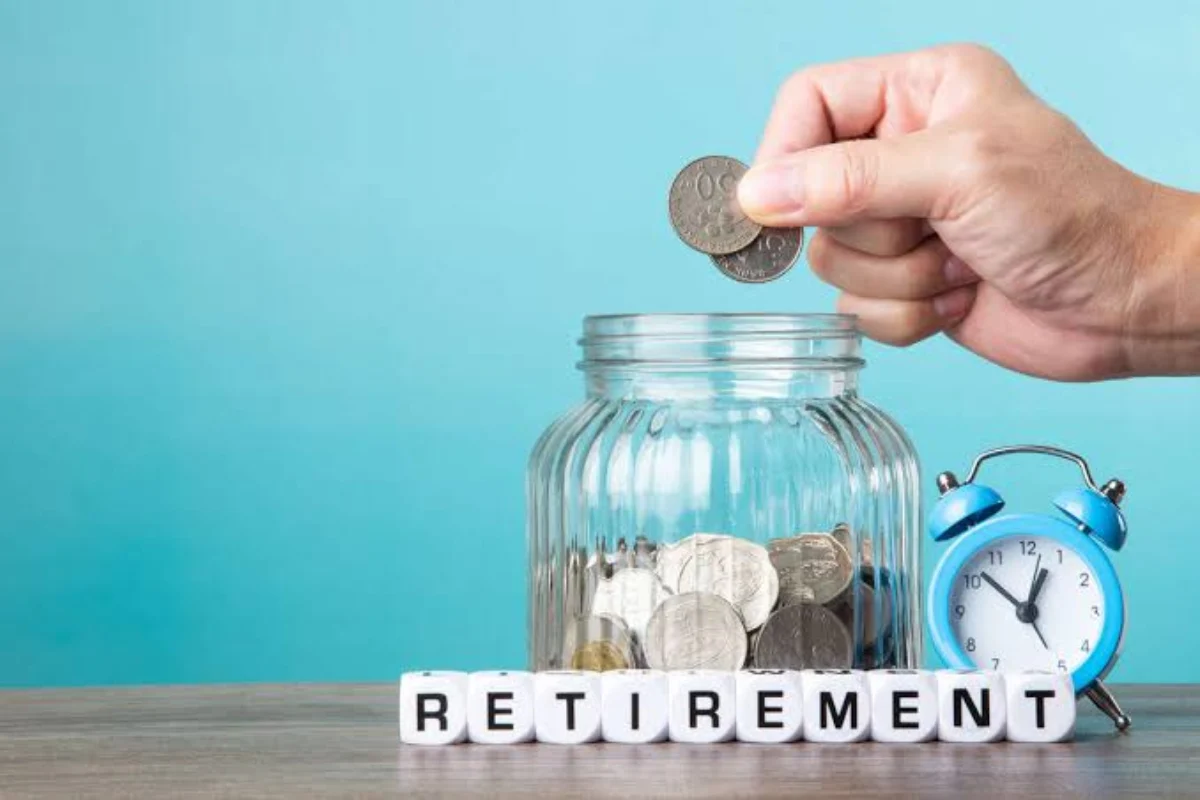
Retirement planning is simplified when you know how much you need to save every month to accumulate a sufficient retirement fund. Your monthly contribution towards retirement will vary based on your current age, age you wish to retire, current monthly expenses, inflation rate, rate of return on investments, and years in retirement.
Regularly set aside a payment towards your retirement rather than saving it at the time you will retire. This is to grow your wealth over a period of time.
This Article Belongs to Retirement Planning
Why Monthly Savings Matter for Retirement
Create compound interest When you start saving early and make regular contributions, the potential of compound interest works better. The sooner you start, the longer your money has to grow – you could even see a small monthly saving add up over time.
Take a 30-year-old who has a longer time frame to save than a 40-year-old. The second person will need to contribute significantly more at the beginning of each month to accumulate a similar pot at the time of retirement.
The trick is to work out how much you need to save for retirement, which will be based on your future potential expenses, and not just pick a random amount each month.
Factors That Determine Monthly Retirement Savings
Several factors influence your required monthly retirement contribution:
Age: Investors who are younger than most others tend to have more time to gather their savings.
Retirement age: the younger you retire, the higher a corpus you will need.
Present expenses: Your current living expenses can be a benchmark for retirement costs.
Inflation: Price increases are likely to further increase what you will have to pay in the future.
Investment return expectation: A higher expected return will decrease the monthly contribution required to be saved, but again there is no guarantee as to that return.
Retirement years: The longer you live, the more the corpus.
Depreciated investments: If you already have investments in the form of EPF, PPF, mutual fund etc, pension etc then this will reduce your amount to Save separately.
How to Calculate Monthly Savings for Retirement
A simple retirement calculation can follow these steps:
1. Estimate Your Future Monthly Expenses
Begin with your current expenses and then project them to retirement with inflation.
E.g. You are currently paying 50,000 a month on your household expenses but that could grow significantly more over 20 or 25 years.
2. Estimate Your Retirement Corpus
Future costs, number of years in retirement, and average return on investments after retirement will influence the size of the corpus you need.
A simplified approach is:
Retirement Corpus = Annual Retirement Expenses Number of Retirement Years
Remember though this is a very simple calculation and there are other factors to take into account such as investment returns in retirement, inflation and if you are going to spend more in retirement.
3. Calculate Your Monthly Investment
Once you know the target corpus, you can use the future-value formula for regular investments.
For a monthly investment:
FV = P × [((1 + r)ⁿ – 1) / r]
Where:
- FV = Future value
- P = Monthly investment
- r = Monthly expected return
- n = Number of monthly investments
This forms the basis of a retirement SIP calculation.
Example of Monthly Retirement Investment
For example, an investor aged 30 years is planning to retire at the age of 60. The investor has 30 years left to invest. To build a corpus of 1 crore assuming 10% of hypothetical return per annum, he will need to contribute roughly Rs 4400 per month.
This calculation is just an example. Investment returns can vary significantly and the corpus required could be even higher depending on future expenses and inflation.
| Investment Period | Illustrative Annual Return | Target Corpus | Approx. Monthly Investment* |
|---|---|---|---|
| 20 years | 10% | ₹1 crore | ₹13,200 |
| 25 years | 10% | ₹1 crore | ₹7,500 |
| 30 years | 10% | ₹1 crore | ₹4,400 |
*Figures are rounded for explanation purposes. Results vary, and actual investment can result in significantly different total return and yield depending on how invested, and the number and frequency of return, interest or dividends.
Monthly Savings for Retirement at Different Ages
Typically, you have to invest more if you begin at a later age, due to less time for the power of compound to work its magic.
| Starting Age | Investment Period to Age 60 | General Approach |
|---|---|---|
| 25 | 35 years | Smaller monthly contribution may be sufficient |
| 30 | 30 years | Moderate monthly investment |
| 35 | 25 years | Higher contribution needed |
| 40 | 20 years | Significantly higher savings may be required |
| 45 | 15 years | Larger contributions and careful planning become important |
These are planning principles rather than fixed investment recommendations.
How to Increase Your Retirement Savings
If you do not believe that your contribution is enough, then you can always make it higher incrementally. You can rise for your retirement monthly investment whenever your salary or business income goes up.
For instance, as against maintaining your SIP at the same level for 25 years, you could increase the contribution by a certain percentage annually. This is also known as a step-up SIP.
You also have to check you retirement plan on a regular basis because income, expenses, inflation and investments’ return can alter.
How Much to Save for Retirement?
There is no single amount that works for everyone. Someone living in a smaller city with low expenses may need a different corpus from someone planning an expensive urban lifestyle.
Your calculation should consider:
- Current monthly expenses
- Expected inflation
- Retirement age
- Expected life expectancy
- Healthcare and insurance costs
- Existing retirement investments
- Expected investment returns
- Other sources of retirement income
Conclusion
How to save the most for retirement is an important aspect of long-term financial planning. You can make the task a little easier by taking advantage of the power of time, and begin saving early and often.
Always get a realistic estimate for your retirement SIP, factor in inflation, and recalculate your retirement corpus every now and then. But, above everything else, do not opt for a fixed monthly sum without taking into account any possible changes in your future expenditure or retirement objectives.