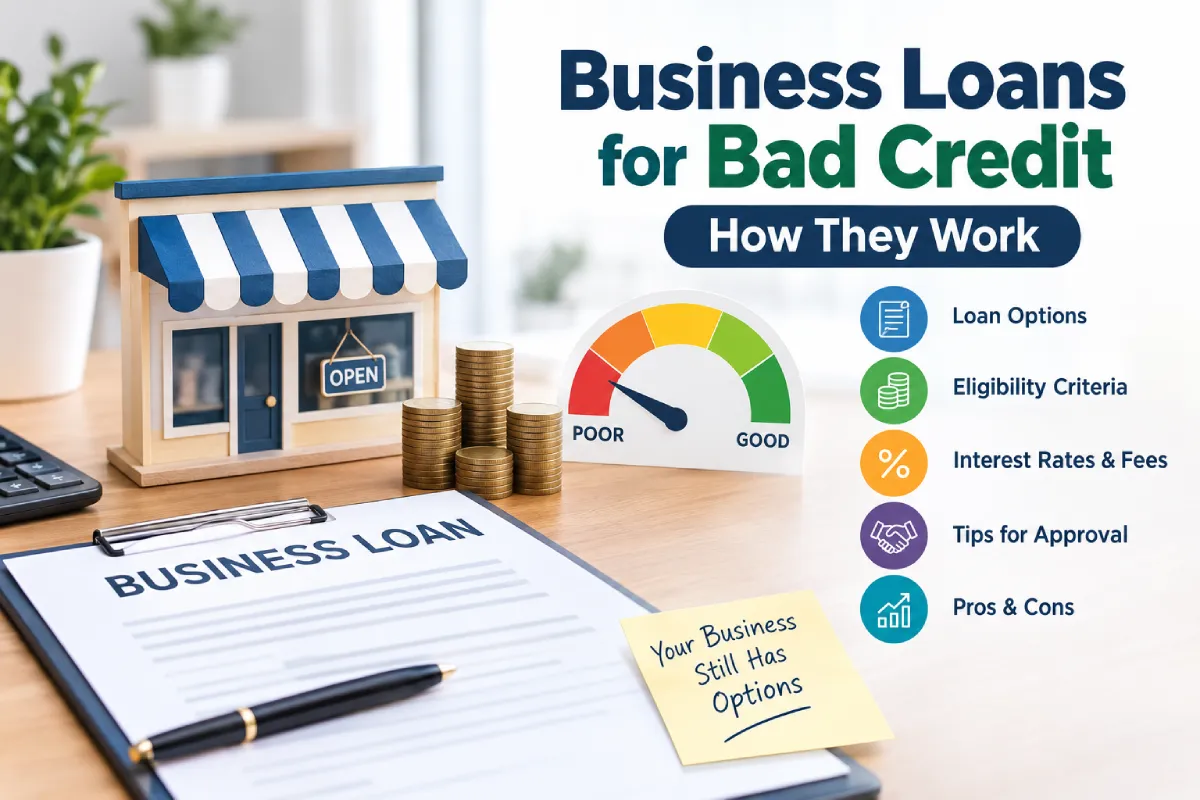
Business Loans for Bad Credit: How They Work
Securing business financing with a bad credit score can be difficult. Generally speaking, traditional lenders rely on credit history as one of the top factors when assessing a business loan application. But bad credit doesn’t always mean bad options for business owners.
Business loans for bad credit are for clients who may not be approved for regular financing due to a low personal or business credit score. They may offer higher interest rates, shorter repayment terms, and/or smaller loan amounts, and may have other conditions.
Knowing how bad credit business financing works will also help a business owner compare products and make a decision in which bad credit financing option best suits his or her needs and ability to pay back.
This Article Belongs to Business Loans
What are Business Loans for Bad Credit?
Business loans for those with bad credit can be used to finance a business. Some lenders will also consider other factors besides bad credit when reviewing your application. Those factors can include cash flow, revenue, time in business, and previous debts.
Some lenders will provide low-credit business loans to borrowers who do not qualify for bank funding.
It can be used as working capital, inventory, equipment, marketing, expansion, payroll, or any other legitimate business expense.
How Do Business Loans for Bad Credit Work?
The basic process is similar to other business loans, but lenders may use additional information when evaluating applicants.
| Step | What Happens |
| Application | The business owner provides personal and business information. |
| Credit review | The lender checks available credit information. |
| Financial assessment | Revenue, cash flow, debts, and business performance may be reviewed. |
| Loan offer | Eligible applicants receive loan terms, rates, and repayment details. |
| Funding | After acceptance and approval, the loan amount is provided. |
| Repayment | The borrower makes scheduled payments according to the agreement. |
Because lenders may consider borrowers with greater credit risk, business funding bad credit can sometimes be more expensive than conventional business financing.
Types of Poor Credit Business Loans
Business owners with weak credit may encounter several financing structures. Availability depends on the lender, business circumstances, and location.
Term Loans
A term loan provides a fixed amount that is repaid over an agreed period. Some alternative lenders offer term loans to businesses that may not qualify for traditional bank financing.
Business Lines of Credit
A business line of credit provides access to a predetermined credit limit. The borrower generally pays interest or fees based on the amount used, depending on the agreement.
Invoice Financing
Businesses with unpaid customer invoices may be able to obtain financing against eligible invoices. The lender’s assessment may focus heavily on the invoices and customers rather than solely on the owner’s credit score.
Equipment Financing
Equipment financing can be used to purchase business equipment. The equipment itself may help secure the financing, potentially reducing the lender’s reliance on the borrower’s credit profile.
What Lenders Consider Besides Credit Score?
A low credit score is important, but it may not be the only factor considered in a bad credit business financing application.
Lenders may evaluate:
- Business revenue and cash flow
- Time in business
- Existing debt obligations
- Bank account activity
- Business plan and intended use of funds
- Collateral or personal guarantees
- Payment history
- Industry and overall business risk
For newer businesses, lenders may place greater emphasis on the owner’s personal credit and business projections because there may be limited business credit history.
Typical Features of Low Credit Business Loans
Terms vary considerably between lenders. The following table illustrates factors borrowers should compare rather than suggesting universal loan terms.
| Feature | What to Check |
| Loan amount | Minimum and maximum amount available |
| Interest rate | Annual rate and how it is calculated |
| Fees | Origination, application, late-payment, or other charges |
| Repayment | Daily, weekly, or monthly payments |
| Loan term | Length of the repayment period |
| Collateral | Whether assets are required |
| Personal guarantee | Whether the owner is personally liable |
A borrower should look at the total cost of financing, not just the advertised interest rate.
Benefits and Risks of Business Loans for Bad Credit
For some businesses, financing can provide access to working capital when traditional lending is unavailable. It may help cover short-term expenses or support an opportunity that could generate additional revenue.
However, borrowers should also consider the risks. Higher costs can increase the pressure on business cash flow. Short repayment periods may result in substantial regular payments, while secured financing can put business assets at risk if the borrower defaults.
How to Improve Your Chances of Approval
Before applying for poor credit business loans, business owners can take steps to strengthen their application:
- Review credit reports for errors.
- Organize recent business financial statements.
- Demonstrate consistent revenue where possible.
- Reduce unnecessary existing debt.
- Prepare a clear explanation of how the funds will be used.
- Compare multiple lenders and financing structures.
Avoid applying for financing without understanding the repayment obligation. Multiple applications and expensive short-term financing can potentially create additional financial pressure.
Are Business Loans for Bad Credit Right for Your Business?
A low credit score does not automatically rule out business financing, but the cost and terms can differ significantly from traditional loans. Business loans for bad credit may provide an option for businesses that need capital but should be evaluated carefully.
Prior to agreeing to an offer, evaluate the interest rate, fees, repayment frequency, total repayment sum, collateral conditions, and penalties for a missed payment. The key thing is that the business has sufficient income from its activities to accommodate the repayment schedule.
Final Thoughts
Business Loans for Bad Credit can be difficult to secure but not impossible. Whether you are looking for a business loan with bad credit or need financing such as a Term Loan, Line of Credit, Invoice Financing, or Equipment Financing.
But bad credit business funding might be more expensive and have tougher terms. By shopping around for the right financing options and only taking on what the business will be able to realistically afford to pay off, unnecessary strain can be avoided.