Money Management International: Services, Fees, Reviews & How It Works
Your Financial Situation Can Get Tough. Past-due balances on credit cards, student loans, vehicle loans, rising expenses, and a number of month-to-month payments begin to strain a household spending budget. If you’re struggling with debt, credit counseling can provide a little structure that will help you comprehend your financial troubles and look into your choices.
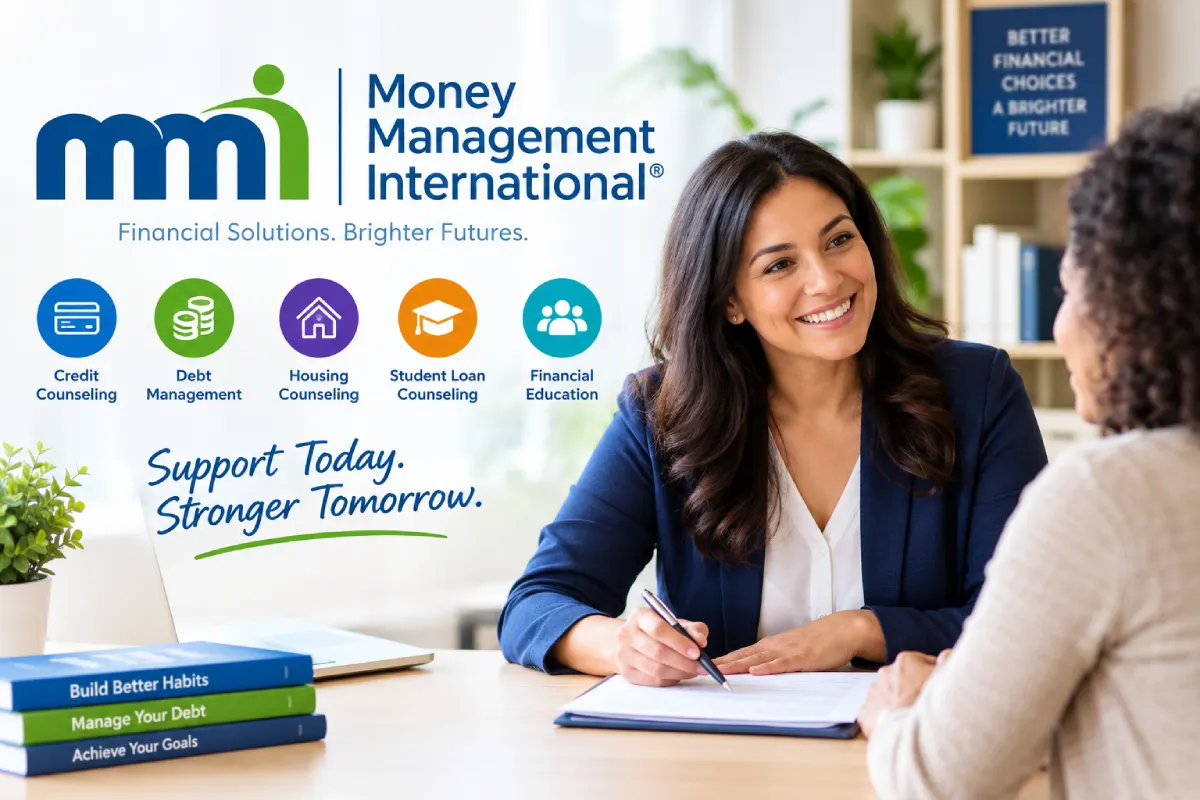
Money Management International (MMI) is a nonprofit credit and financial education and counseling organization in the United States. We are not a bank and do not lend money to consumers as a personal-loan provider. We provide help and guidance to consumers and their families by reviewing their financial situations and exploring options to help them manage their debt.
This detailed breakdown explores Money Management International MMI’s debt management programs & services, cost, reviews, pros & cons, and what to think about before using the company.
This Article Belongs to Money Management
What is Money Management International?
Money Management International is a non-profit credit counselling organization dedicated to providing help for consumers faced with financial difficulties. Its services are offered to help people get a handle on their debt, develop realistic budgets, and find a plan to pay.
MMI offers counseling for a variety of financial situations such as Credit Card Debt, Housing Issues, Student Loans, Bankruptcy Needs, and more as well as financial literacy.
Organization’s structure: MMI is a 501c3 non-profit. MMI claims to be accredited by the Council on Accreditation (COA), a member of the National Foundation for Credit Counseling (NFCC), and offers HUD-approved housing counseling services.
Key facts about Money Management International
| Feature | Details |
| Organization | Money Management International |
| Common abbreviation | MMI |
| Organization type | Nonprofit |
| Primary focus | Financial and credit counseling |
| Lending | Does not provide consumer loans |
| Debt management | Debt Management Plans |
| Debt resolution | Debt Resolution Plans for eligible accounts |
| Counseling | Credit, housing, bankruptcy, student loan and other counseling |
| Financial education | Guides, educational materials and counseling |
| Availability | Primarily serves consumers in the United States |
MMI’s role is therefore different from that of a lender. Rather than giving a consumer a new loan to pay existing debts, the organization can help evaluate existing obligations and determine whether a structured debt repayment program could be appropriate.
What Is Money Management International MMI Known For?
Nonprofit credit counseling and debt management is what many people associate with the word Money Management International MMI.
The organization makes an array of financial counselors available to clients who will review the income, expenses, debts, and other finances. Depending upon the situation, the counselor can offer solutions.
These may include:
- Budgeting assistance
- Credit counseling
- Debt Management Plans
- Debt Resolution Plans
- Financial education
- Housing counseling
- Student loan counseling
- Bankruptcy counseling
- Credit report education
- Homebuyer counseling
- Reverse mortgage counseling
An important point is that counseling does not automatically mean that a consumer needs to enroll in a debt management program. Counseling can also be useful for people who simply want to understand their options.
How Does Money Management International Debt Management Work?
One of the best-known MMI programs is its Money Management International debt management service.
A Debt Management Plan, commonly called a DMP, is designed to help eligible consumers repay certain unsecured debts through a structured payment arrangement.
The Consumer Financial Protection Bureau explains that credit counseling organizations can help consumers create budgets and establish debt management plans that consolidate payments to participating creditors.
Instead of managing several creditor payments independently, a consumer generally makes a consolidated payment to the counseling organization. Funds are then distributed to participating creditors according to the agreed repayment plan.
Typical Debt Management Plan process
The process can generally be explained in the following stages:
1. Financial assessment
The first step is understanding the consumer’s financial position.
A counselor may review:
- Monthly income
- Household expenses
- Credit card balances
- Interest rates
- Minimum payments
- Other unsecured debts
- Available disposable income
This helps determine whether a DMP may be appropriate.
2. Debt review
The counselor reviews the consumer’s accounts and determines which debts may be eligible for the program.
Not every creditor or debt type necessarily qualifies, so consumers should ask which accounts can be included.
3. Repayment plan
If a DMP is appropriate, MMI develops a repayment structure based on the consumer’s financial circumstances and participating creditors.
The plan may involve modified interest rates or other concessions from participating creditors.
4. Monthly payment
The consumer makes an agreed payment according to the DMP schedule.
Instead of making multiple payments individually, the program can simplify repayment by distributing funds to participating creditors.
5. Debt repayment
The payments are made until the enrolled debts have been paid, as specified in the plan.
The actual payoff period will depend on debt balances, amount of monthly payment, terms with creditors, and interest rates.
What Types of Debt Can MMI Help With?
Debt management programs are generally designed for unsecured consumer debt.
Examples can include certain:
- Credit card balances
- Personal debts
- Unsecured lines of credit
- Other eligible unsecured accounts
However, eligibility is not automatic.
Secured debts such as mortgages and many auto loans generally work differently because they are backed by collateral.
Consumers should ask MMI which specific accounts qualify before enrolling.
Debt types and possible treatment
| Debt type | May be suitable for a DMP? | Notes |
| Credit cards | Often | Eligibility depends on creditor |
| Unsecured personal debt | Potentially | Individual account review required |
| Medical debt | Depends | Program eligibility can vary |
| Mortgage | Generally no | Secured debt |
| Auto loan | Generally no | Secured debt |
| Student loans | Usually handled separately | MMI has dedicated counseling |
| Tax debt | Generally separate | May require specialist assistance |
The exact treatment can vary, so consumers should not assume that every debt can be included.
Money Management International Services
The range of Money Management International services extends beyond debt management.
MMI offers counseling and educational resources designed for consumers at different stages of their financial lives.
1. Credit Counseling
Credit counseling can help consumers understand their current financial situation.
A counselor may help identify:
- Spending patterns
- Debt repayment challenges
- Budgeting opportunities
- Potential repayment strategies
- Credit-related concerns
Credit counseling can be useful even if the consumer ultimately decides not to enroll in a DMP.
2. Debt Management Plans
DMPs provide structured repayment assistance for eligible unsecured debts.
The objective is to make repayment more organized and potentially more manageable.
3. Debt Resolution Plans
MMI also offers debt resolution services for certain eligible accounts.
This approach differs from a traditional DMP because debt resolution can involve negotiating with creditors regarding repayment of eligible delinquent or charged-off accounts.
Consumers should understand the differences between debt management and debt resolution before choosing either option.
4. Housing Counseling
MMI provides housing-related counseling for consumers dealing with issues such as:
- Homebuying
- Mortgage concerns
- Foreclosure-related challenges
- Reverse mortgages
- Housing affordability
5. Student Loan Counseling
Student loan repayment can be complicated because borrowers may have multiple repayment options.
MMI provides student loan counseling intended to help consumers better understand their available choices.
6. Bankruptcy Counseling
People considering bankruptcy may need to complete required counseling from an approved provider.
MMI provides pre-filing bankruptcy counseling and related educational services.
7. Financial Education
MMI also publishes financial education resources covering areas such as:
- Budgeting
- Credit
- Saving
- Debt management
- Financial planning
- Homeownership
Money Management International Fees
Understanding Money Management International fees is an important part of evaluating any debt counseling service.
Many basic counseling and educational services may be offered at no cost. However, consumers should not assume that every service is free.
Debt Management Plans generally involve fees.
According to MMI’s published information, DMP fees can vary based on factors such as the consumer’s location and debt circumstances.
Example MMI DMP fee information
| Fee category | Published information |
| Average setup fee | Approximately $37–$38 |
| Average monthly fee | Approximately $26–$35 |
| Maximum setup fee | $75 |
| Maximum monthly fee | $69 |
These figures should be treated as general published information rather than a guaranteed price for every consumer. MMI states that eligible consumers may receive reduced or waived fees.
Before enrollment, consumers should confirm:
- Exact setup fee
- Exact monthly fee
- Whether fees vary by state
- Whether they qualify for a fee reduction
- Total estimated program cost
- What happens to fees if they leave the program
A small monthly fee can become significant over several years, so understanding the total cost is important.
Are Money Management International Counseling Services Free?
Many counseling and educational services may be available at no charge.
For example, a consumer can seek financial counseling to understand their options without necessarily committing to a DMP.
However, some specialized services and structured repayment programs can have fees.
This distinction is important:
Free counseling does not necessarily mean a free debt management program.
Consumers should ask for the exact cost of the service they are considering before agreeing to enrollment.
Money Management International Reviews: What Do Customers Say?
Searching for Money Management International reviews can provide additional insight into the experiences of consumers who have interacted with the organization.
However, online reviews should be interpreted carefully.
Different review platforms measure different things, and customer experiences can vary depending on the type of service used.
MMI publishes customer satisfaction information on its own website. Because these figures are company-reported, consumers may also want to review independent sources when researching the organization.
The Better Business Bureau has profiles for Money Management International and related local operations. BBB profiles can include ratings, complaints, customer reviews, and other business information. However, BBB itself explains that its rating is not an endorsement of a business.
What to look for when reading reviews
Rather than focusing only on the overall rating, consider whether reviews mention:
- Counselor communication
- Payment processing
- Clarity of program terms
- Fees
- Creditor interactions
- Account management
- Online tools
- Length of the repayment process
- Customer service responsiveness
A review from someone using a DMP may be very different from a review from someone who only received financial counseling.
Money Management International Pros and Cons
Understanding potential advantages and limitations can help consumers conduct a more balanced evaluation.
Potential advantages
- Nonprofit organizational structure
- Credit counseling services
- Debt Management Plans
- Multiple financial counseling services
- Housing counseling
- Student loan counseling
- Bankruptcy counseling
- Financial education resources
- Potential creditor concessions through eligible programs
- May provide a structured repayment approach
Potential limitations
- Not every debt qualifies
- DMPs can involve setup and monthly fees
- Some creditors may not participate
- A DMP can restrict the use of enrolled credit cards
- Consumers must follow the repayment schedule
- Individual credit effects can vary
- Debt management is not suitable for every financial situation
These factors should be considered alongside the consumer’s individual financial circumstances.
Money Management International vs. Debt Consolidation Loans
MMI’s debt management program is not the same as a debt consolidation loan.
A consolidation loan involves borrowing new money and using that money to repay existing debts. A DMP generally does not involve taking out a new loan.
| Factor | MMI Debt Management Plan | Debt Consolidation Loan |
| New loan required | No | Yes |
| Main objective | Structured debt repayment | Combine debts into new loan |
| Interest | May be reduced through creditor concessions | Based on lender’s terms |
| Monthly program fee | May apply | Loan fees may apply |
| Credit requirements | Different from loan underwriting | Usually lender-dependent |
| Credit cards | May need to be closed/restricted | Depends on borrower |
| New borrowing | Not required | Required |
Neither structure automatically suits every borrower. Consumers should compare the total cost, repayment period, interest rate, fees, and eligibility requirements.
Does MMI Affect Your Credit Score?
A common question about debt management is whether participation will affect a consumer’s credit.
A DMP itself is not a loan. However, enrolling accounts in a DMP can change how those accounts are handled.
For example, a consumer may be required to stop using certain credit cards or close enrolled accounts. This can affect available credit and therefore potentially affect credit utilization.
Creditors may also report accounts according to their own policies.
MMI states that the organization itself is not listed as a creditor on the consumer’s credit report. Consumers should nevertheless discuss potential credit-reporting implications with MMI and their creditors before enrollment.
Factors that can affect credit during debt management
- Existing payment history
- Account balances
- Credit utilization
- Account closures
- Creditor reporting practices
- New credit applications
- Continued payment behavior
Therefore, there is no single credit-score outcome that applies to everyone.
Money Management International Debt Resolution vs. Debt Management
It is important not to confuse the two.
Debt Management Plan
A DMP is generally intended to help consumers repay eligible debts under a structured arrangement.
Debt Resolution Plan
A debt resolution program may involve negotiating repayment of certain delinquent or charged-off accounts.
The two programs can have different eligibility requirements and consequences.
| Feature | Debt Management | Debt Resolution |
| Main objective | Structured repayment | Negotiated resolution |
| Account status | Often current or delinquent eligible accounts | Generally delinquent/charged-off eligible accounts |
| Creditor negotiation | May involve concessions | May involve settlement negotiations |
| Credit implications | Can vary | Can be significant depending on circumstances |
| Consumer should review | Fees and repayment schedule | Fees, settlement terms and potential tax/credit consequences |
Anyone considering debt resolution should understand the potential consequences before entering the program.
Who May Consider Money Management International?
Money Management International may be worth researching for consumers who:
- Have several credit card balances
- Struggle to manage multiple monthly payments
- Want professional credit counseling
- Need help creating a realistic budget
- Want to explore a DMP
- Prefer not to take out another consolidation loan
- Need housing counseling
- Need student loan guidance
- Need bankruptcy counseling
- Want financial education
However, consumers with a small amount of debt may find that a self-managed repayment strategy is sufficient.
Similarly, people dealing with legal, tax, or highly complex financial problems may need advice from a qualified attorney, tax professional, or financial professional.
How to Prepare for an MMI Counseling Session
Before speaking with a counselor, gathering financial information can make the conversation more useful.
Income information
- Salary
- Freelance income
- Benefits
- Other regular income
Debt information
- Creditor names
- Current balances
- Interest rates
- Minimum payments
- Account numbers where appropriate
Monthly expenses
- Rent or mortgage
- Utilities
- Food
- Transportation
- Insurance
- Medical expenses
- Childcare
- Other recurring expenses
Financial goals
Think about what you want to accomplish.
For example:
- Reduce monthly payments
- Pay off credit cards
- Create a realistic budget
- Avoid missing payments
- Understand debt options
- Improve financial organization
Having this information ready can make it easier to evaluate whether a proposed program fits your budget.
Alternatives to Money Management International
MMI is only one possible source of debt assistance.
Depending on your financial circumstances, alternatives may include:
Self-managed debt repayment
Consumers with manageable debt may create their own repayment strategy.
Two commonly discussed approaches are:
Debt avalanche: Focus additional payments on the highest-interest debt first.
Debts snowball: Focus additional payments on the smallest balance first.
Debt consolidation loan
A consumer may use a new loan to repay multiple debts and then make one loan payment.
Balance transfer
Some credit cards offer promotional balance-transfer rates, subject to eligibility and terms.
Debt settlement
The process of settling debts with your creditors can be a way to pay less than you owe on certain debts. Debt settlement, however, can have serious consequences and risks, so consumers should research thoroughly.
Consumers in a distressed financial condition may choose bankruptcy. Because bankruptcy can have legal and financial ramifications, it may be best to consult a lawyer.
Bankruptcy
Consumers in a distressed financial condition may choose bankruptcy. Because bankruptcy can have legal and financial ramifications, it may be best to consult a lawyer.
How to Compare Debt Management Companies
If you are considering MMI or another credit counseling organization, compare several factors rather than focusing on advertising claims alone.
| Comparison factor | What to check |
| Organization type | Nonprofit or for-profit |
| Accreditation | Relevant accreditation and memberships |
| Counseling cost | Free or paid |
| DMP setup fee | Exact amount |
| Monthly fee | Exact amount |
| Creditor participation | Which creditors participate |
| Repayment period | Estimated duration |
| Interest concessions | Potential rates or terms |
| Customer support | Phone and online options |
| Reviews | Multiple independent sources |
| Cancellation policy | Terms for leaving |
| Credit impact | Potential reporting effects |
Consumers should request written program information and understand the agreement before enrolling.
Is Money Management International Legitimate?
Money Management International is an established nonprofit credit counseling organization. It provides financial counseling and debt-related services rather than functioning as a traditional lender.
However, legitimacy and suitability are separate questions.
A legitimate organization may still offer a program that is not appropriate for a particular consumer.
Before enrolling, consumers should verify:
- Program eligibility
- Exact fees
- Creditor participation
- Payment amount
- Repayment timeline
- Cancellation terms
- Credit implications
Independent research and comparison can help consumers make an informed financial decision.
Important Things to Know Before Enrolling
A Debt Management Plan is not a way to eliminate debt instantly.
Consumers generally still need to repay the enrolled debt according to the program terms.
There may also be restrictions on using credit cards included in the program.
A DMP can make payments more organized, but it requires commitment. Skipping a payment or ending the program could impact the usual amount you will owe.
Consumers should also steer clear of taking on large new debt while repaying another loan..
Frequently Asked Questions About Money Management International
Is Money Management International a debt consolidation company?
MMI has debt management plans but is not actually a debt consolidation company. DMPs do not typically offer a new loan.
Does MMI provide loans?
No. MMI is a credit counseling organization rather than a consumer lender.
What are Money Management International fees?
Fees depend on the service and consumer circumstances. DMPs generally involve a setup fee and ongoing monthly fee. MMI states that eligible consumers may qualify for reduced or waived fees.
Is Money Management International nonprofit?
Yes. MMI describes itself as a 501(c)(3) nonprofit organization.
Does MMI offer debt management?
Yes. MMI offers Debt Management Plans for eligible consumers and accounts.
Can MMI help with credit card debt?
Credit card debt is one of the types of unsecured debt that may be eligible for a DMP, depending on the creditor and account.
Does MMI guarantee debt reduction?
Consumers should not assume that debt reduction or specific creditor concessions are guaranteed. Terms depend on individual circumstances and participating creditors.
Are Money Management International reviews reliable?
Reviews can provide useful insight, but they represent individual experiences. It is better to examine multiple independent sources and consider the specific service discussed in each review.
Final Thoughts on Money Management International
Money Management International MMI is a nonprofit organization that provides credit counseling and various forms of financial assistance (Debt Management Plans, Debt Resolution Plans, housing counseling, student loan counseling, bankruptcy counseling, financial education).
If a person is searching for Money Management International MMI, the only thing I should remember if advertising the business is that the main lead is that Money Management International MMI has debt counseling and a way to pay off debt.
If you are looking into Money Management International fees, make sure you get the exact fee information for your situation before registration.