Credit Line on UPI: Meaning, Benefits, Eligibility, Uses & How It Works
Last Updated: September 15, 2026
Digital payment ecosystem has revolutionized all aspects of Indian finances – how you spend, transfer and even pay your day-to-day expenses. Credit Line on UPI comes as a seamless extension to digital payments, where eligible customers can leverage pre- approved credit facility on UPI-enabled apps.
Rather than relying on the balance in a bank account, a customer fulfilling specified requirements can link a approved line of credit to the UPI and utilise the limit that is available for specified transactions. The facility was introduced by RBI and NPCI to encourage broader access to credit and facilitate easier digital lending.
This article explains UPI credit line, how credit line through UPI works, its benefits, eligibility, charges, repayment considerations and the precautions users should take.
This Article Belongs to Credit Debt
What is Credit Line on UPI?
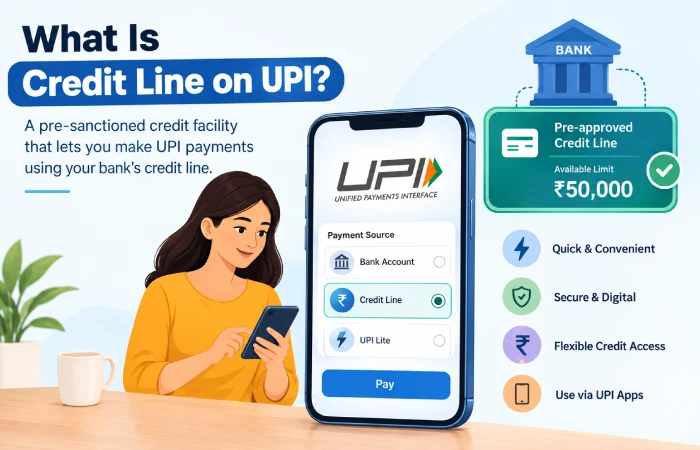
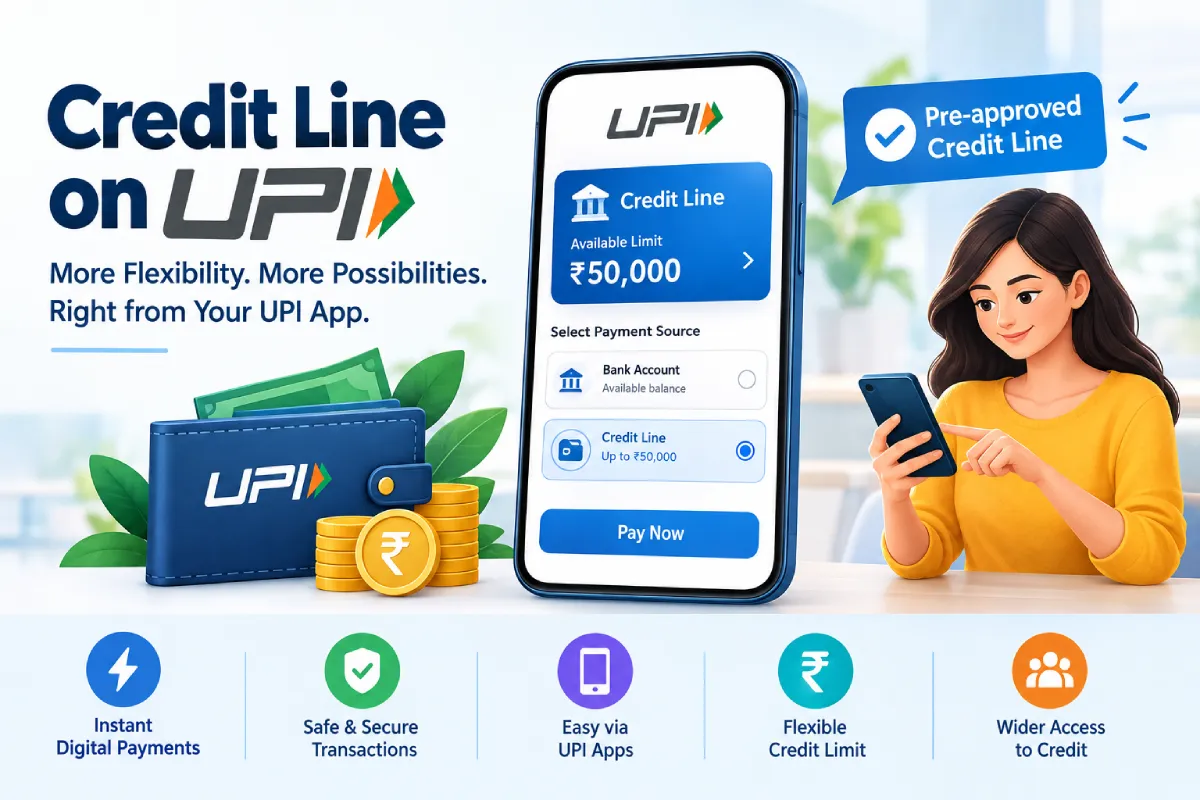
Credit Line on UPI is a digital payment facility that allows an eligible customer to link a pre-sanctioned credit line provided by a bank to a UPI-enabled application.
In simple terms, a bank may approve a credit limit for a customer. Instead of accessing that credit only through a traditional loan account or card, the customer can link the eligible credit line to UPI and use it for supported payments.
The RBI specifically discusses pre-sanctioned credit lines through UPI and the expansion of the facility to Small Finance Banks. The framework also allows UPI apps, including bank and third-party apps, to discover and link eligible credit lines.
Example
In case a bank approves a credit line of 50,000 for an eligible customer. If the customer associates the facility with a supported UPI app, the available credit may be utilized for the eligible UPI transactions. In case 5,000 is utilized, then the balance amount becomes 5,000 and the remaining available limit may be 45,000, depending on the bank’s guidelines.
| Particular | Example |
| Approved credit line | ₹50,000 |
| Amount used | ₹5,000 |
| Remaining available limit | ₹45,000 |
| Outstanding credit | ₹5,000 |
The actual limit, interest, repayment period and permitted transactions depend on the issuing bank and product terms.
How Does UPI Credit Line Work?
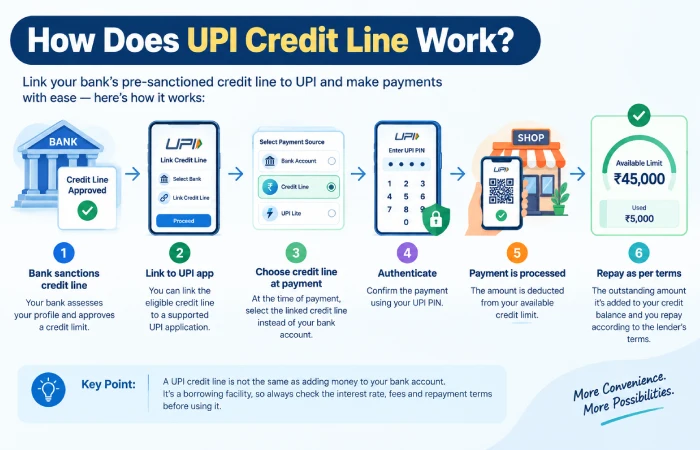
The basic process combines a bank’s credit facility with the UPI payment infrastructure.
The bank first assesses the customer and sanctions an eligible credit line. The customer can then link the facility to a supported UPI application. After successful setup, the credit line can appear as a payment account/source where permitted.
A typical process looks like this:
Bank sanctions credit → Customer links credit line to UPI → Customer selects credit line at payment → UPI authentication → Payment is processed → Amount becomes outstanding → Customer repays according to terms
NPCI’s Credit on UPI material illustrates a flow in which the customer selects the issuing bank, chooses the eligible credit-line account and confirms the account for use through UPI.
Important distinction
A UPI credit line is not the same as adding money to your bank account. It is a borrowing facility. When you use it, you generally create an outstanding credit obligation that must be repaid according to the issuer’s terms.
What Is a UPI Credit Line?
A UPI credit line is a sanctioned borrowing limit that can be linked to UPI for eligible digital transactions.
Unlike a conventional personal loan where a fixed amount may be disbursed upfront, a credit line can provide access to a specified limit, with the customer using the facility as needed, subject to availability and product rules.
For example, if you have a ₹1 lakh sanctioned limit, you may not necessarily need to borrow the entire amount. If you use ₹10,000, your outstanding borrowing may be based on the amount actually used, depending on the product structure.
The exact interest calculation, minimum repayment, billing cycle and other conditions vary between lenders.
What Does Credit Line Through UPI Mean?
Credit line through UPI means using an eligible bank-provided credit facility as a payment source within the UPI ecosystem.
Traditional UPI transactions generally draw money directly from a linked bank account. With a supported credit line, the customer can instead choose the eligible credit facility for applicable transactions.
This can be useful for customers who want the convenience of UPI while managing short-term credit requirements.
However, users should remember that convenience does not eliminate the cost of borrowing. Before using the facility, customers should check:
- Interest rate
- Interest-free period, if offered
- Repayment date
- Minimum repayment amount
- Late-payment charges
- Processing or other applicable fees
- Credit limit
- Permitted transaction categories
- Conditions for increasing or reducing the limit
NPCI’s launch information specifically notes that participating banks can establish digital credit products with applicable interest-free periods, interest rates and schedules of charges.
What Is a Pre-Approved Credit Line on UPI?
A pre-approved credit line on UPI refers to a credit facility that a bank has already sanctioned for an eligible customer and that can subsequently be linked to UPI, subject to the applicable product and technical requirements.
“Pre-approved” does not mean unlimited or automatically available to every customer. The bank determines eligibility and the sanctioned amount based on its own credit policies.
A customer may see an offer or eligible credit account in a banking or UPI application. Before accepting it, the customer should carefully review the lender’s terms.
Factors that may influence eligibility
Depending on the lender, eligibility may consider factors such as:
- Credit history
- Income or repayment capacity
- Existing relationship with the bank
- Existing loans or credit facilities
- Internal risk assessment
- Account activity
- KYC status
- Bank-specific eligibility criteria
There is no universal eligibility formula applicable to every UPI credit-line product.
Key Features of Credit Line on UPI
The major features can be summarized as follows:
| Feature | Description |
| Digital credit access | Eligible credit can be accessed through supported digital payment channels |
| UPI integration | Credit line can be linked to an eligible UPI application |
| Pre-sanctioned facility | The bank determines the approved limit |
| Convenient payments | Customers can use UPI’s familiar payment interface for eligible transactions |
| Multiple UPI apps | NPCI’s framework supports discovery and linkage through bank and third-party UPI apps |
| Reusable limit | Depending on the product, repayment may restore available credit |
| Bank-specific pricing | Interest and charges depend on the issuer |
| Digital servicing | Eligible UPI apps can support customer lifecycle services |
NPCI states that all UPI apps, including bank and third-party apps, are intended to be able to discover and link eligible credit lines on UPI, subject to the relevant ecosystem requirements.
Benefits of UPI Credit
1. Convenient digital payments
One of the biggest advantages is convenience. Customers familiar with UPI do not necessarily need to learn an entirely new payment process to use an eligible credit facility.
2. Quick access to sanctioned credit
If a customer already has an approved credit line, connecting it to UPI can make eligible spending easier.
3. No need to carry cash
The facility can be useful for digital transactions where the merchant accepts UPI and the transaction qualifies for payment using the credit line.
4. Potentially useful for short-term needs
A credit line may provide flexibility when an unexpected expense arises and the customer has sufficient repayment capacity.
5. Integrated digital experience
Credit, payment authentication and transaction history can managed digitally through supported banking or UPI applications.
6. Wider access to formal credit
The RBI and NPCI introduced Credit Line on UPI with the objective of expanding access to credit and promoting financial inclusion.
UPI Credit vs Traditional UPI Payment
It is important to understand the difference between ordinary UPI payments and payments made using a credit facility.
| Factor | Regular UPI | Credit Line on UPI |
| Primary source | Bank account balance | Eligible sanctioned credit line |
| Borrowing involved | No | Yes |
| Interest | Normally not applicable to the payment itself | May apply according to credit terms |
| Repayment | No separate credit repayment | Required according to lender terms |
| Credit limit | Based on account balance/payment limits | Based on sanctioned credit limit |
| Credit risk | No borrowing from the transaction | Customer assumes repayment obligation |
Regular UPI is fundamentally a payment system for transferring money between bank accounts, while Credit Line on UPI adds an eligible credit source to the payment ecosystem. NPCI describes UPI as an instant payment system developed by NPCI and built over the IMPS infrastructure.
UPI Credit Facility: Who Can Use It?
The availability of a UPI credit facility depends on the participating bank, the customer’s eligibility and the specific credit product.
A customer may need to:
- Have an eligible relationship with the issuing bank.
- Complete required KYC procedures.
- Meet the bank’s credit assessment criteria.
- Have a sanctioned credit line.
- Use a supported UPI application.
- Accept the applicable terms and conditions.
- Set up or authenticate the facility as required by the bank.
Not every UPI user automatically receives a credit line.
How to Use a Credit Line UPI Payment
The exact interface differs between UPI applications and banks, but the general process may look like this:
- Check eligibility: Check your bank’s app or contact the bank to determine whether you have an eligible credit line.
- Open a supported UPI app: Use a UPI application that supports the relevant credit-on-UPI functionality.
- Link the credit line: Select the relevant bank and eligible credit-line account and follow the authentication process.
- Make an eligible payment: At a participating merchant or supported payment point, choose UPI as the payment method.
- Select the credit line: If eligible for the transaction, select the linked credit facility instead of your regular bank account.
- Authenticate: Complete the required UPI authentication, such as entering your UPI PIN.
- Track the outstanding amount: After the transaction, monitor the credit used and remaining available limit through the relevant banking or UPI application.
NPCI’s UPI documentation confirms that UPI transactions are authenticated using a UPI PIN, which users should never share with another person.
Where Can Credit Line on UPI Be Used?
The permitted use of a credit line depends on the bank, UPI app, merchant category and applicable rules.
Potentially supported use cases can include eligible merchant payments such as:
- Retail purchases
- Grocery shopping
- Restaurants
- Online shopping
- Utility-related payments where permitted
- Other participating merchant transactions
However, not every UPI transaction necessarily qualifies for payment using every credit-line product.
Users should therefore check the issuer’s current terms instead of assuming that a credit line can be used for all UPI payments.
Interest and Charges on UPI Credit
One of the most important aspects of a UPI credit facility is understanding its cost.
The availability of UPI does not mean that borrowing through a credit line is free. The bank or lender may charge interest and other applicable fees according to the product agreement.
Possible charges may include:
| Charge | What to check |
| Interest | Rate and method of calculation |
| Processing fee | Whether applicable |
| Late-payment charge | Penalty for delayed repayment |
| Other fees | As specified by the lender |
| Taxes | Applicable taxes on relevant charges |
| Annual or facility charges | Whether the product has recurring charges |
Some products may provide an interest-free period, while others may calculate interest differently. NPCI’s framework explicitly provides for banks to establish interest-free periods, interest rates and schedules of charges for digital credit products.
Always read the lender’s Key Facts Statement, agreement, fee schedule and repayment terms before accepting credit.
Advantages and Disadvantages of Credit Line on UPI
Advantages
- Convenient access to eligible credit
- Familiar UPI payment experience
- Digital setup and servicing
- Potentially useful for short-term expenses
- No need to carry a separate payment instrument for eligible transactions
- Can provide an additional payment source when bank-account funds are insufficient
Disadvantages
- It is borrowed money and must be repaid
- Interest may apply
- Late repayment can result in additional charges
- Easy access can encourage unnecessary spending
- Eligibility and transaction restrictions may apply
- Credit terms vary by lender
- Overuse can increase financial pressure
The biggest benefit—easy access—can also become the biggest risk if customers spend beyond their repayment capacity.
Credit Line on UPI vs Credit Card
A credit line on UPI and a credit card are both forms of credit, but they are not identical.
| Feature | Credit Line on UPI | Credit Card |
| Payment interface | UPI app | Card/online card payment |
| Physical card | Generally not required | Usually associated with a card account |
| UPI integration | Core feature | Depends on card and UPI eligibility |
| Credit limit | Bank-approved | Issuer-approved |
| Interest | Product-specific | Card-specific |
| Rewards | Depends on product | Often available |
| Acceptance | Subject to UPI/merchant/product rules | Subject to card network/merchant acceptance |
| Repayment | As per credit-line terms | As per card billing terms |
The best option depends on the user’s spending habits, costs, rewards, repayment terms and transaction requirements.
Is Credit Line on UPI Safe?
UPI has authentication and security steps, but these tips will help you to shop online in a safe manner.
According to NPCI, users should not share their UPI PIN with anyone. UPI PIN is use for authorizing transactions with your bank account and, your bank or UPI support team will never ask for it.
Safety tips
- Never share your UPI PIN: Keep your UPI PIN a secret.
- Verify the merchant: Always look for merchant name and amount to avoid scammers.
- Don’t approve unknown requests: Never authenticate a payment simply because someone asks you to.
- Avoid suspicious links: Use the official banking or UPI application instead of unknown links.
- Check your transactions: Review your payment and credit activity regularly.
- Contact the bank quickly if something looks suspicious: Report unauthorized transactions through the appropriate bank or UPI support channel.
Does UPI Credit Affect Your Credit Score?
The impact depends on the lender, credit product and reporting practices.
Because a UPI credit line is a borrowing facility, customers should understand whether the facility and its repayment behaviour are reported to credit information companies.
Timely repayment can help maintain a healthy credit profile where the facility is reported, while missed or delay payments can potentially have a negative impact.
Before using a credit line, check the lender’s documentation for information about credit bureau reporting.
Things to Check Before Taking a UPI Credit Line
Before accepting a pre-approved credit line on UPI, consider the following checklist:
- Credit limit: Do not assume that a larger approved limit means you should spend more.
- Interest rate: Investigate the interest rate and how it is calculated.
- Repayment schedule: Make sure you know when you will be require to make each payment.
- Grace or interest-free period: If the lender has an interest free period make sure you know the conditions under which it can be use.
- Fees: Make sure you know what processing fees, late fees and others may apply.
- Transaction restrictions: Confirm where and for which types of transactions the credit line can be use.
- Credit reporting: Check whether the facility and repayment history are reported to credit bureaus.
- Cancellation or closure rules: Understand what happens if you decide to discontinue the facility.
Frequently Asked Questions About Credit Line on UPI
What is Credit Line on UPI?
Credit Line on UPI is a facility that allows eligible customers to link a bank-sanctioned credit line to UPI and use it for permitted transactions.
Is UPI credit the same as a bank loan?
It is a form of credit, but the structure can differ from a conventional personal loan. The customer receives access to a sanctioned credit limit rather than necessarily receiving a fixed loan amount upfront.
Can everyone get a UPI credit line?
No. The issuing bank determines eligibility and credit limits based on its own policies and the specific product.
Is credit line through UPI interest-free?
Not necessarily. Interest and applicable charges depend on the lender and product. Some products may provide an interest-free period subject to specific conditions.
Can I use UPI credit for every QR payment?
Not necessarily. Use is subject to the product’s terms, merchant category, participating institutions and applicable restrictions.
Can I use my UPI credit line to send money to another person?
The permitted transaction types depend on the applicable credit product and rules. Users should not assume that a credit line works exactly like a normal bank-account balance for person-to-person transfers.
Does a UPI credit facility require a physical card?
The Credit Line on UPI framework is designed to enable eligible credit lines through UPI, so a physical card is not necessarily require for the UPI-based payment experience. Availability depends on the issuing product.
What happens if I don’t repay the credit?
You may face interest, late-payment charges or other consequences according to the lender’s agreement. Delayed repayment may also affect your credit profile where the facility is reported.
Final Thoughts
Credit Line on UPI represents an important development in India’s digital-credit ecosystem. By connecting eligible bank-sanctioned credit facilities with UPI, it can make access to short-term credit more convenient and integrated with everyday digital payments.
The key terms—UPI credit line, credit line through UPI, pre-approved credit line on UPI, UPI credit, UPI credit facility and credit line UPI payment—all relate to the broader idea of accessing eligible credit through the UPI ecosystem.
But convenience is not free money. Customers should consider the interest rate, fee structure, repayment schedule, limits on transactions and ability to repay credit before tapping a credit line.
Used responsibly, a UPI-linked credit facility can provide flexibility. Used without a repayment plan, it can quickly increase financial obligations. The right approach is therefore to treat every UPI credit transaction as borrowing and use it only when the cost and repayment commitment are clearly understood.