Retirement Planning Calculator: Estimate Corpus, Savings & Monthly Investment
Retirement Planning Calculators make it easy to plan for your retirement. You will be able to understand how much corpus you will need to put together for the future by using this retirement planning calculator. With the help of this calculator, you will get an approximate calculation of the retirement corpus that you will need.
Using a retirement calculator in India can be useful for individuals who are in the process of planning their finances in India to assess whether their initial savings and investments will be sufficient to fund their future needs or how much they should plan to invest periodically to build up your target corpus.
Learn how retirement calculators operate, what you’ll need to get the most from them, why inflation is an important factor to consider and how to crunch your retirement numbers.
This Article Belongs to Retirement Planning
What is a Retirement Planning Calculator?
A retirement planning calculator is a financial planning tool that calculates how much money you will probably need after you retire and how much you will need to save or invest prior to your retirement.
The calculator generally considers two stages:
- Accumulation phase: The years during which you earn, save and invest for retirement.
- Retirement phase: The period after retirement when you use your accumulated corpus to meet living expenses.
If your age is 35, and you want to retire at 60, you will have around 25 years left for building up your corpus. The calculator can then project the future value of your expenses adjusted for inflation and compare it to your likely investments.
This result is not a forecast of future performance. This is an estimate based on the assumptions input into the calculator.
For additional guidance on estimating retirement needs, investors can refer to the SEBI Retirement Planning Guide, which explains factors such as retirement age, life expectancy, inflation and investment returns when estimating a retirement corpus.
Why Use a Retirement Calculator in India?
Retirement planning in India takes into account many factors such as inflation, return on investments, mounting health care costs and modern-day lifestyles. Choosing to save Rs. 5000/ Rs 10,000 every month may not be sufficient to understand if you will be able to achieve that target in the future.
A retirement calculator India can help you answer questions such as:
- How much could my current savings become by retirement?
- What retirement corpus might I need?
- How much should I invest every month?
- How can inflation affect my future expenses?
- How long could my retirement corpus potentially last?
- What happens if I retire earlier or later?
It helps to put some of the assumptions into a numerical calculation that can be used as an initial benchmark when you do your financial planning.
How Does a Retirement Planning Calculator Work?
A retirement calculator is a way to estimate a retirement requirement using your current financial situation as well as assumptions about what the future will look like.
The main inputs normally include:
| Input | What It Means |
| Current age | Your age when planning begins |
| Retirement age | The age at which you expect to stop working |
| Current monthly expenses | Your present lifestyle expenses |
| Expected inflation | Estimated annual increase in expenses |
| Current retirement savings | Existing investments or savings earmarked for retirement |
| Expected investment return | Assumed annual return before retirement |
| Post-retirement return | Assumed return during retirement |
| Life expectancy | Estimated number of years the corpus may need to support you |
| Existing monthly investment | Current amount being invested regularly |
| Desired retirement lifestyle | Expected spending requirements after retirement |
Once these figures are entered, the calculator estimates your potential future expenses and retirement corpus.
Understanding the Retirement Corpus
Retirement corpus is the money you have accumulated to be used during the period when you are retired. If your current monthly household expenditure is Rs 50,000, you may not need Rs 50,000 a month.
Cost inflation simply means the prices of things go up over time. This is evident when the cost of a monthly bill is 50,000 now and increases by 6% every year.
Here’s why a retirement corpus calculator would account for inflation when it estimates your retirement requirement.
A Simple Inflation Illustration
Imagine someone has a current monthly expenditure of 50,000 and is planning to retire in 25 years time.
Estimated 6% per year, inflation rate of 50,000 in the future:
₹50,000 × (1.06)²⁵ ≈ ₹2.15 lakh per month
This is an illustration rather than a prediction. Actual inflation may be higher or lower, and different categories of expenses can increase at different rates.
Retirement Planning Calculator Formula
Although online calculators perform the calculations automatically, understanding the basic concepts can help you interpret the results.
The future value of an expense can be estimated using:
Future Expense = Current Expense × (1 + Inflation Rate)ⁿ
Where:
- Current Expense = your current monthly or annual expense
- Inflation Rate = assumed annual inflation
- n = number of years until retirement
Retirement corpus calculation becomes complicated since it accounts for the expected investment return, withdrawal rate, and years of retirement.
For instance, when you retire at age 60 and are saving for expenses until age 85, your retirement plan may have to draw for roughly 25 years.
So a good calculator will take into account the accumulation period and the withdrawal period.
Retirement Savings Calculator: How Much Should You Save?
Use a retirement savings calculator to help you determine how much you’ll have to save for retirement.
Your required savings can depend on:
Current age + retirement age + current savings + investment returns + inflation + retirement expenses + retirement duration
A 25-year-old has a longer time horizon compared to a 45-year-old. The longer time period would allow more opportunities to invest regularly and/or enjoy the benefits of compounding.
This does not imply that younger investors can use this to get out of putting money into retirement funds. Because they are starting earlier, they may have time to stretch this out.
Example of Different Starting Ages
Consider a hypothetical retirement age of 60.
| Starting Age | Years Until Retirement | General Planning Implication |
| 25 | 35 years | Longer accumulation period |
| 30 | 30 years | Long investment horizon |
| 35 | 25 years | Moderate accumulation period |
| 40 | 20 years | Higher importance of savings rate |
| 45 | 15 years | More limited accumulation period |
| 50 | 10 years | Greater focus may be required on retirement preparation |
These figures do not indicate how much an individual should invest. The appropriate amount depends on income, expenses, assets, liabilities, investment strategy and retirement goals.
Retirement Investment Calculator and Investment Returns
A retirement investment calculator assumes a rate of return to project how investments might perform over time.
Let’s take this user example: Someone invests 20,000 every month for 25 years. The end results can vary quite a lot depending on what the estimated investment return is.
Yet don’t get carried away and assume a “guaranteed” return.
Investments linked to the market can go up and down, and the past does not predict the future. As such, conservative assumptions can help when planning for your longer-term future.
The calculator should be used to understand scenarios rather than promise a particular outcome.
Monthly Retirement Contribution Calculator
A monthly retirement contribution calculator works in the opposite direction.
Instead of asking:
“How much could my investments grow?”
you can ask:
“How much should I contribute every month to work towards my target corpus?”
For example, assume the following hypothetical scenario:
| Parameter | Example |
| Current age | 35 years |
| Retirement age | 60 years |
| Investment period | 25 years |
| Target retirement corpus | ₹2 crore |
| Existing retirement savings | ₹20 lakh |
| Expected annual return | 10% |
| Monthly contribution | Calculator-dependent |
The actual monthly contribution would depend on the assumptions used by the calculator, including whether contributions increase annually.
This distinction is important because a person who increases their contribution as their income grows may have a different retirement trajectory from someone who keeps the contribution fixed.
The Role of Inflation in Retirement Planning India
Inflation is one of the most important assumptions in retirement planning India.
If the price of goods and services increases over time, the purchasing power of a fixed amount of money decreases.
Imagine that someone requires ₹60,000 per month today. If inflation averages 6% for 25 years, the amount required to maintain a similar purchasing level could be much higher in the future.
Healthcare deserves particular attention because medical expenses can become a significant part of retirement spending.
A retirement plan should therefore consider:
- Regular household expenses
- Housing costs
- Healthcare
- Insurance premiums
- Travel and leisure
- Family responsibilities
- Emergency expenses
- Taxes
- Major one-time expenses
Retirement Expenses: What Should You Include?
One common mistake is calculating retirement requirements using only current household expenses.
A more complete approach separates expenses into different categories.
| Expense Category | Examples |
| Essential expenses | Food, utilities, housing and transportation |
| Healthcare | Insurance, medicines and medical treatment |
| Lifestyle | Travel, hobbies and entertainment |
| Family support | Assistance to children or other family members |
| Financial commitments | Loans or other obligations |
| Emergency reserve | Unexpected expenses |
| Major purchases | Home maintenance, vehicle replacement or other large expenses |
Some expenses may disappear after retirement, while others may increase.
For example, commuting costs may fall after retirement, but travel or healthcare expenses could increase. Your calculator inputs should therefore reflect your expected lifestyle rather than simply copying today’s expenses.
How Compounding Can Help Retirement Savings
Compounding means that investment returns can generate additional returns over time.
Suppose you invest regularly and the investment earns returns. Over a long period, the returns can become part of the investment base, potentially allowing future returns to be earned on both the original contributions and accumulated returns.
This is one reason the length of the investment period matters.
A simplified example:
| Investment Period | General Effect of Compounding |
| 5 years | Limited time for compounding |
| 10 years | Greater accumulation potential |
| 20 years | Compounding becomes more significant |
| 30 years | Long-term growth can have a substantial effect |
Actual results depend on the investment, contribution pattern and realised returns.
Retirement Calculator Example
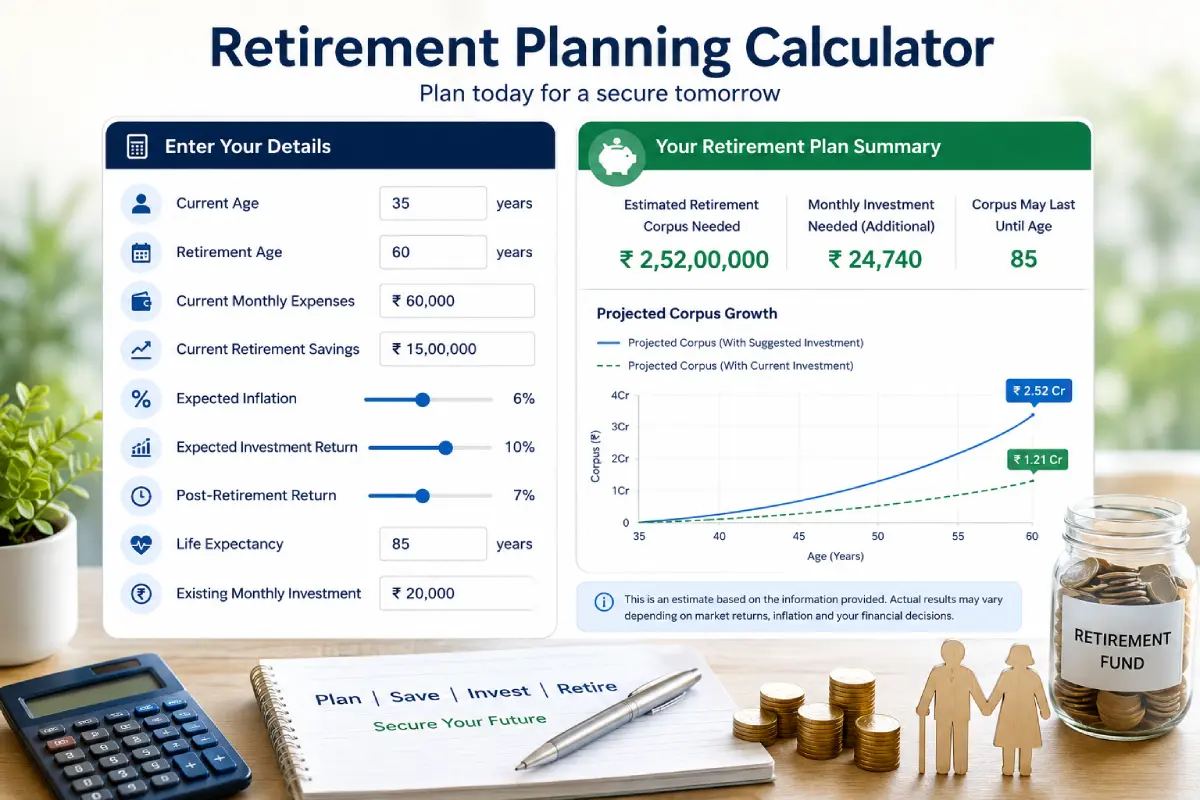
Consider a hypothetical person with the following details:
| Parameter | Hypothetical Value |
| Current age | 35 |
| Retirement age | 60 |
| Current monthly expenses | ₹60,000 |
| Current retirement savings | ₹15 lakh |
| Inflation assumption | 6% |
| Expected pre-retirement return | 10% |
| Expected post-retirement return | 7% |
| Retirement planning period | 25 years |
The calculator can use these assumptions to estimate future expenses and the potential retirement corpus.
The important point is that changing any major assumption can significantly change the result.
For example, increasing the retirement age from 60 to 65 provides five additional years for accumulation while potentially reducing the number of years for which the corpus must support withdrawals.
Similarly, increasing the monthly investment or annual step-up can change the projected corpus.
Retirement Planning Calculator vs Retirement Corpus Calculator
The two terms are often used interchangeably, but they can focus on slightly different calculations.
| Calculator | Main Purpose |
| Retirement Planning Calculator | Provides an overall retirement planning estimate |
| Retirement Corpus Calculator | Estimates the corpus potentially required at retirement |
| Retirement Savings Calculator | Estimates potential growth of retirement savings |
| Retirement Investment Calculator | Estimates potential investment growth |
| Monthly Retirement Contribution Calculator | Estimates regular contributions required towards a target |
A comprehensive retirement calculator may combine all these functions.
Conclusion
A retirement calculator can be the first step to long term planning. Instead of a target savings figure, you factor in your current expenses, inflation, age at which you want to retire, post retirement investment return, current savings and time to retirement.
When it comes to retirement planning india, the key is less about building a huge target corpus and more about knowing how that target was built and updating your assumptions as your finances change.