Mutual Fund SIP, Returns, Fees & Tax Basics
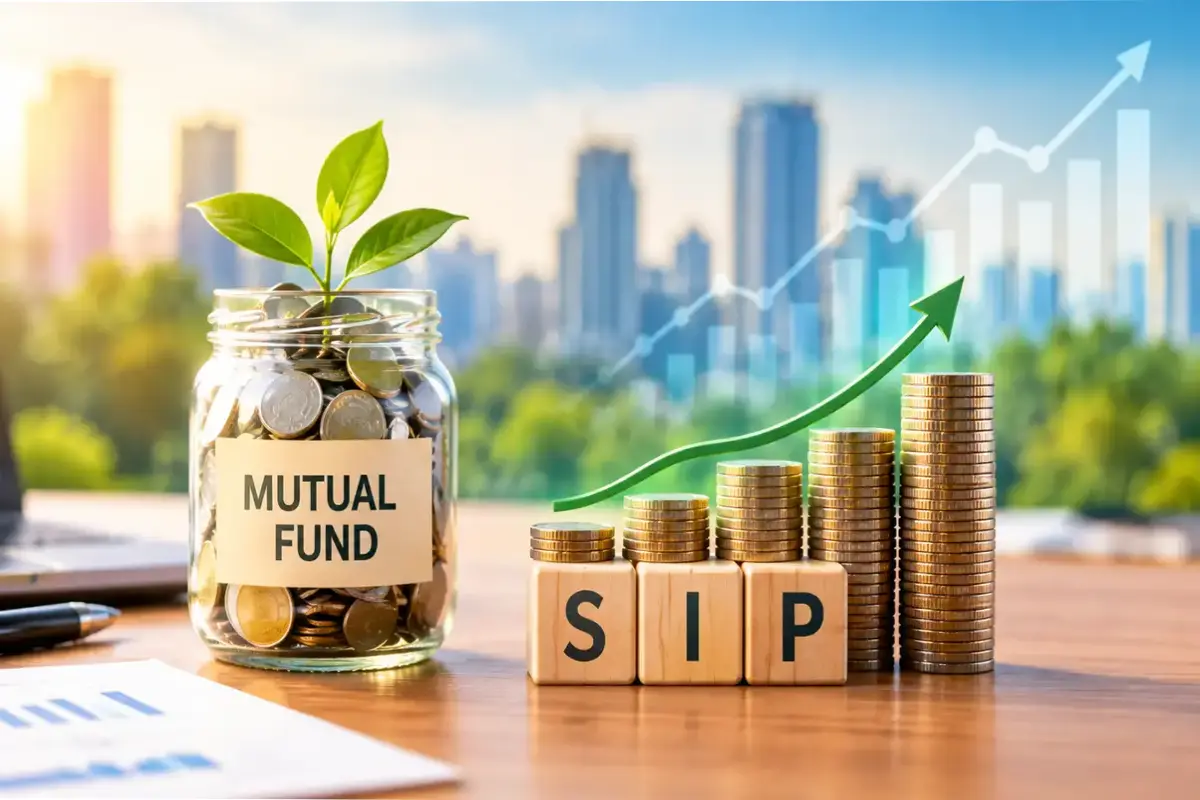
Mutual funds are a common choice for wealth creation for many, as they are managed investment portfolios. Investors can go for a mutual fund SIP or a lump-sum investment in the funds, based on their income, the kind of wealth creation they seek and their investment view. It’s important to understand fund returns, charges and taxation.
This Article Belongs to Mutual Funds
What Is a Mutual Fund SIP?
What is SIP? The full form of SIP in Mutual Funds is Systematic Investment Plan. It is a scheme where investors choose to invest an amount at regular intervals (monthly) in a mutual fund.
For instance, by investing 5,000 each month, you will end up investing a total of 60,000 in a year, or the total amount invested before accounting for returns.
SIPs can encourage disciplined investing and may help average the purchase cost over different market conditions. However, SIPs do not guarantee profits, and mutual fund returns depend on the performance of the underlying investments.
Understanding Mutual Fund Returns
Mutual fund returns represent the growth or decline in the value of your investment. Returns can vary depending on the type of fund, market conditions, investment period and portfolio performance.
Common ways to measure mutual fund performance include:
| Return Measure | What It Shows |
|---|---|
| Absolute Return | Overall gain or loss over a period |
| CAGR | Annualised return over a multi-year period |
| XIRR | Annualised return for investments made at different times, such as SIPs |
For SIP investments, XIRR is particularly useful because each instalment is invested on a different date.
Past performance should not be treated as a guarantee of future returns. Investors should consider their goals, investment horizon and risk tolerance along with historical performance.
Mutual Fund Fees and Charges
Before investing, it is important to understand mutual fund fees because costs can affect your overall investment outcome.
The main cost is the expense ratio, which represents the annual operating expenses charged by the mutual fund scheme. It is generally reflected in the scheme’s NAV rather than being separately deducted from your bank account.
Other possible charges include:
- Exit load: A fee that may apply when units are redeemed within a specified period.
- Transaction-related charges: Certain transactions may involve applicable charges or statutory costs.
- Taxes and statutory levies: These may apply separately depending on the transaction and applicable rules.
Always check the latest scheme documents and the fund house’s disclosures before investing.
SIP vs Lump Sum
Both methods can be suitable in different circumstances.
| Feature | SIP | Lump Sum |
|---|---|---|
| Investment Pattern | Regular instalments | One-time investment |
| Market Timing | Reduces dependence on one entry point | More exposed to entry-point market level |
| Suitable For | Regular income and disciplined investing | Available surplus amount |
| Cash Flow | Smaller periodic amounts | Large amount at once |
| Risk Management | Spreads investments over time | Entire amount invested at one time |
A SIP can be convenient for salaried investors who receive regular income. A lump-sum investment may be considered when an investor has a substantial amount available and understands the associated market risk.
Mutual Fund Taxation in India
Mutual fund taxation depends on factors such as the type of mutual fund, the nature of the investment and the holding period. Tax rules can also change, so investors should check the latest rules before making investment or redemption decisions.
For equity-oriented mutual funds, capital gains are generally classified as short-term or long-term based on the applicable holding period. Debt-oriented and other non-equity funds can have different tax treatment.
Tax may also arise when mutual fund units are redeemed or transferred at a profit. The applicable rate and exemptions depend on the prevailing income-tax rules.
Investors should maintain records of purchases, redemptions and capital gains for accurate tax reporting.
How to Choose a Mutual Fund
Before starting a SIP or making a lump-sum investment, consider:
- Investment objective: Match the fund with goals such as retirement, education or wealth creation.
- Risk level: Understand whether the fund invests in equity, debt or a combination of assets.
- Time horizon: Long-term goals may allow investors to tolerate more market fluctuations.
- Expense ratio: Compare costs among similar schemes.
- Past performance: Review performance over different periods rather than relying on a single year.
- Fund portfolio: Check the scheme’s major holdings and investment strategy.
Conclusion
Investing through mutual fund SIP is a disciplined approach to investing while lump sum could be suitable for investors who have sizeable amount of funds to invest. You need to have knowledge about mutual fund returns, mutual fund fees and mutual fund taxation before you invest. As mutual funds are market-linked schemes, investors should analyze risk, costs, taxes, and financial goals than just the returns.